Cash Out Hard Money Loans: Unlock Your Arizona Property Equity in 2026
September 18, 2026How to Leverage Home Equity with Hard Money: The 2026 Arizona Guide
Why wait sixty days for a bank to tell you “no” when your property is already sitting on a six-figure goldmine? You know your Arizona home or investment property has massive value. You’ve watched the Phoenix and Scottsdale markets hold steady. Yet, traditional lenders treat your equity like a hostage. They demand endless tax returns and perfect credit scores while your next big move slips away. The fastest way to leverage home equity hard money is to stop thinking like a traditional borrower and start thinking like a savvy investor who values speed over paperwork.
You deserve a faster way to win. This 2026 guide reveals how to bypass the bureaucracy and secure the capital you need in as little as 7 to 21 days. We’ll explore the latest Arizona lending thresholds, the power of business-purpose loans, and how asset-based approvals prioritize your property’s value over your personal credit score. It’s time to stop asking for permission from a bank and start using the wealth you’ve already built to fund your next investment or business venture.
Key Takeaways
- Stop waiting on bank approvals and start using your property’s value as the ultimate leverage for fast-moving business opportunities.
- Master the 70% Rule to calculate your usable equity and determine exactly how much liquidity your Arizona property can provide.
- Learn the strategic differences between a slow HELOC and the speed you gain when you leverage home equity hard money for tactical moves.
- Follow our punchy 5-step guide to move from a rough valuation to full funding in as little as seven to twenty-one days.
- Partner with a local Scottsdale-based expert who understands the Valley’s unique market and offers direct access to capital without the red tape.
What Does It Mean to Leverage Home Equity with Hard Money?
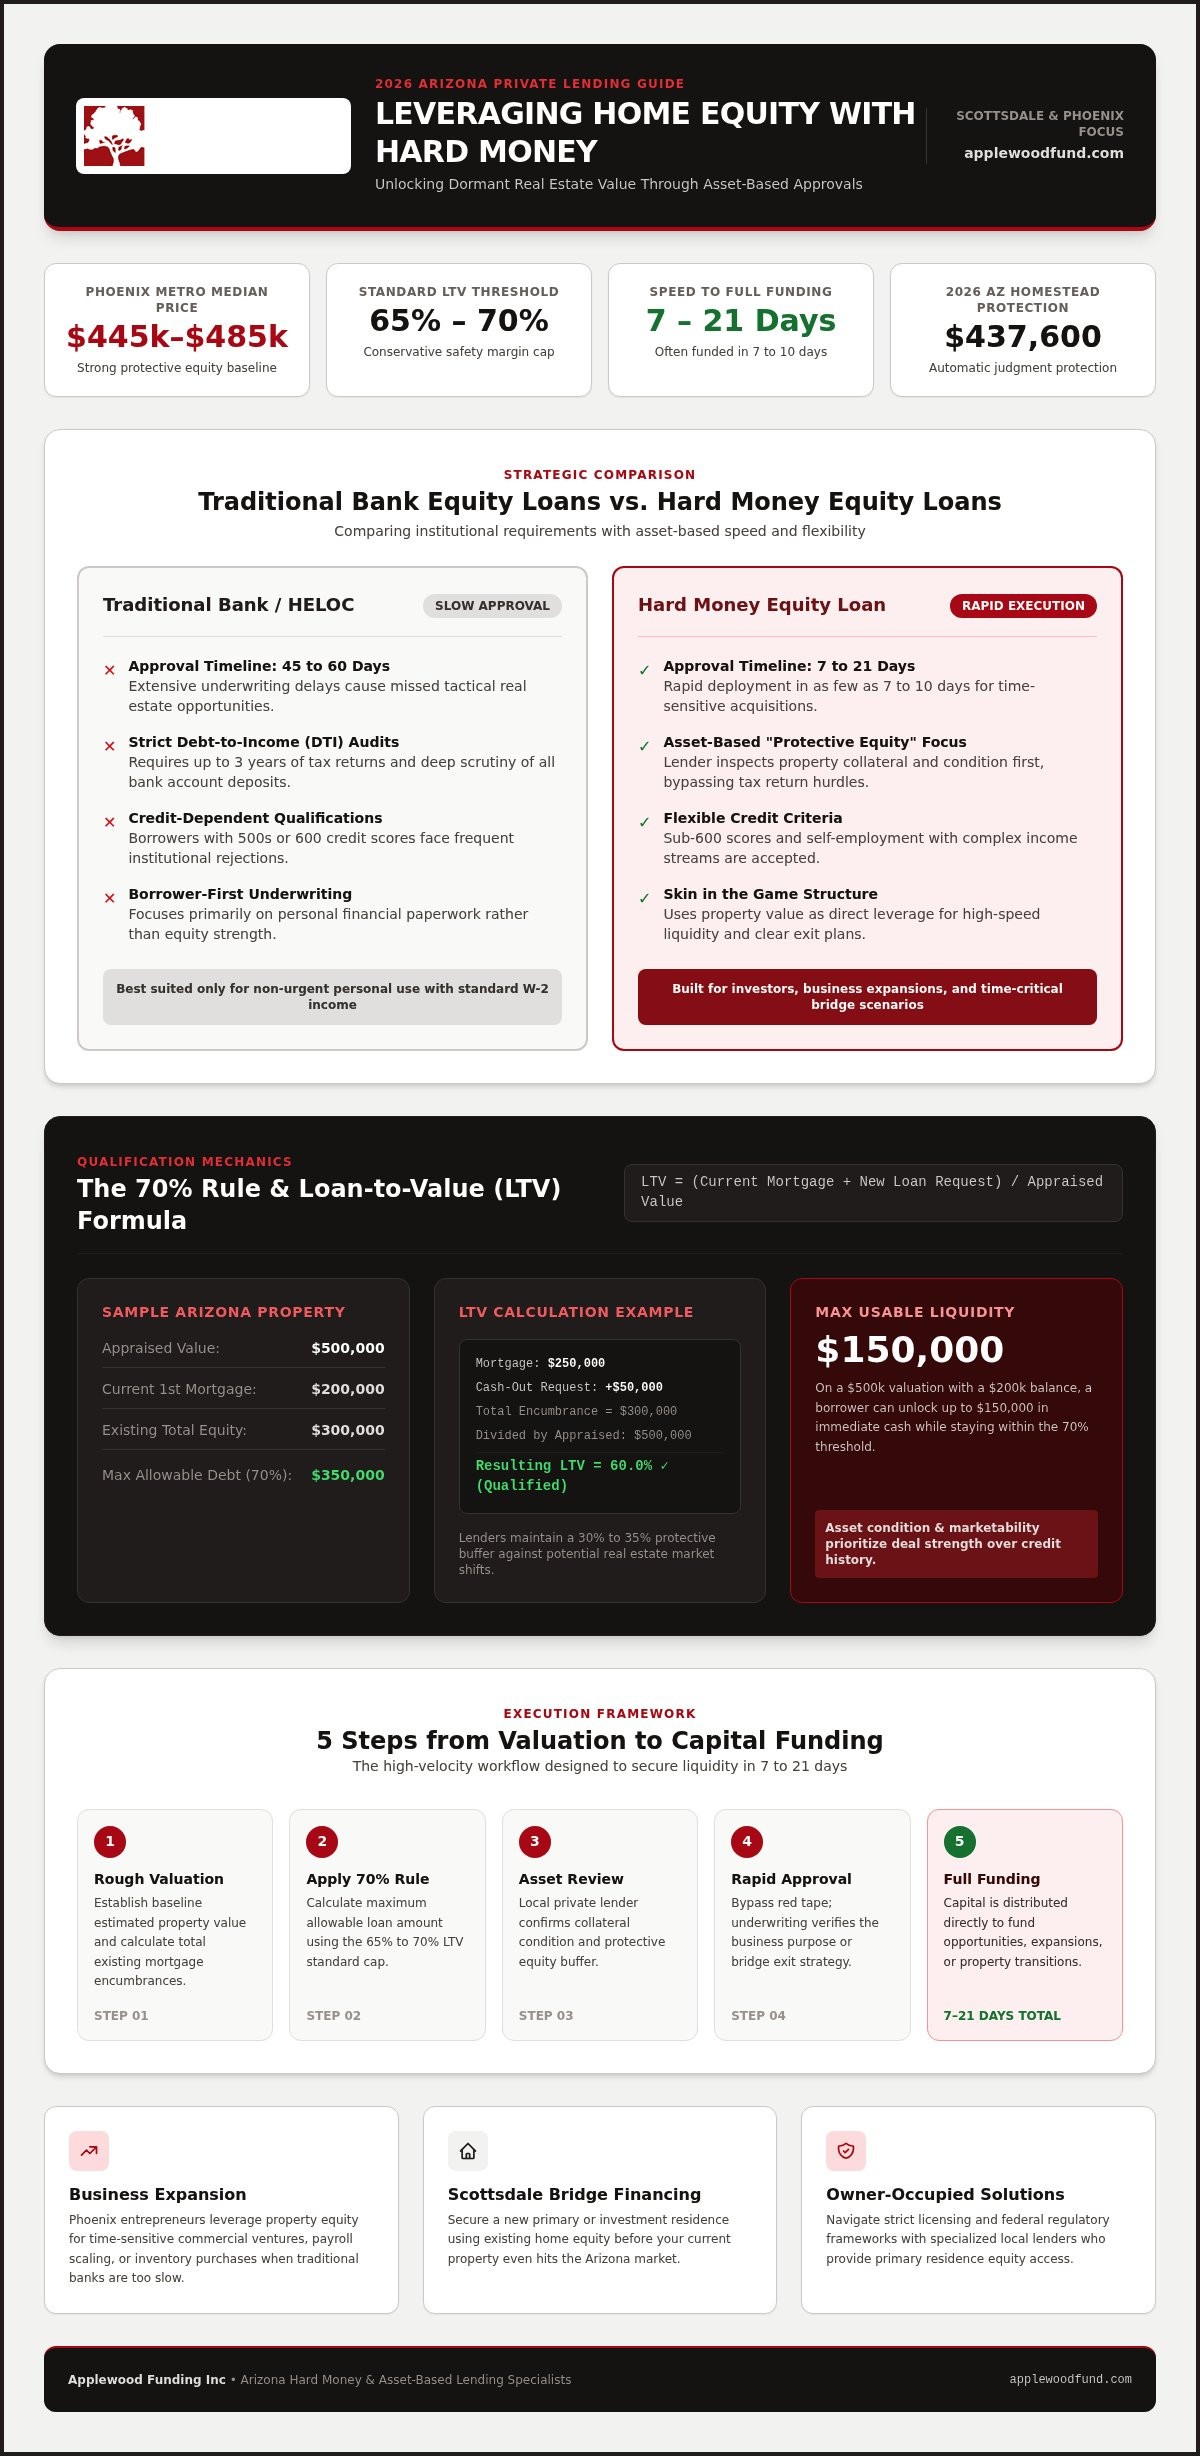
Equity isn’t just a figure on your monthly mortgage statement. It’s dormant capital waiting for a purpose. In 2026, Arizona homeowners are sitting on record levels of wealth, with median sales prices in the Greater Phoenix metro holding between $445,000 and $485,000. To leverage home equity hard money means you’re unlocking that paper wealth to fuel a real-world move. You’re using the value of your property as the engine for a short-term, high-speed loan that doesn’t care about the red tape of traditional banking.
Most hard money loans are asset-based. This means the lender looks at the collateral first and the borrower second. If you have enough “protective equity”—the gap between what you owe and what the home is worth—you have a deal. It’s a bridge designed to get you from your current situation to a profitable exit. Whether you’re a business owner or a seasoned investor, you’re using what you already own to buy what you want next.
Hard Money vs. Traditional Home Equity Loans
Banks are obsessed with your Debt-to-Income (DTI) ratio. They’ll dig through three years of tax returns and question every small deposit in your checking account. Hard money lenders focus on Loan-to-Value (LTV). They want to know if the asset is secure. This shift in focus changes everything for your timeline. A traditional bank might take 45 to 60 days to close a home equity loan. A private lender can often fund your request in 7 to 10 days. Don’t let a 600 credit score stop your progress. When the equity is solid, the approval is simple. You’re trading a slightly higher interest rate for the speed and certainty that banks simply can’t offer in a fast-moving market.
Why Arizona Homeowners Choose Private Capital
Timing is the most valuable currency in Arizona real estate. Entrepreneurs in Phoenix use these loans to fund time-sensitive business expansions or inventory purchases when an opportunity suddenly appears. In Scottsdale, savvy buyers use their existing equity as bridge financing to secure their next primary residence before their current one even hits the market. You’re bypassing the bureaucratic “no” and moving straight to the “yes.” At Applewood Funding, we specialize in these high-energy transitions. We understand that in 2026, waiting two months for a bank is the same as losing the deal. We provide the liquidity you need to stay aggressive and profitable.
Assessing Your Equity: Can You Qualify for a Hard Money Cash-Out?
Before you plan your next move, you need to know the real number. It isn’t just about what your neighbor’s house sold for last month. To leverage home equity hard money, you must understand “protective equity.” This is the buffer that makes a private lender feel secure. If your home is worth $500,000 and you owe $200,000, you have $300,000 in equity. But you can’t touch all of it. Lenders want to ensure that even if the market dips, their investment is safe. They prioritize the property’s condition and marketability over your personal tax returns. If the asset is strong, the deal is alive.
Your credit score might be in the 500s. You might be self-employed with complex income. In the world of private capital, these aren’t deal-breakers. We look at the “skin in the game.” Arizona’s automatic homestead exemption protects up to $437,600 in 2026 from involuntary judgments, but it doesn’t stop you from voluntarily using that equity to grow your business. When you offer your property as collateral, you’re showing the lender you’re serious. They respond with speed that a traditional bank can’t match.
Calculating Your Loan-to-Value (LTV) Ratio
The math is simple but brutal. Use this formula: (Current Mortgage + New Loan Request) / Appraised Value. For example, if you have a $250,000 first mortgage and want a $50,000 cash-out on a $500,000 home, your LTV is 60%. Most Arizona hard money lenders cap this ratio at 65% to 70% to maintain a conservative safety margin. This FTC guide on home equity loans explains how these liens work, but remember that private capital moves much faster than the banks mentioned there. LTV is the safety margin that allows private lenders to say yes when banks say no.
The ‘Owner-Occupied’ Hard Money Distinction
Most private lenders won’t touch a primary residence. They’re afraid of the federal regulations and the paperwork. We aren’t. Securing Owner Occupied Hard Money Loans is a rare path that requires specific licensing and deep local knowledge. While out-of-state firms hide behind Dodd-Frank restrictions, we help Arizona homeowners use their primary residence equity for business purposes. Maybe you need to inject capital into your Phoenix startup or fund a quick flip in Glendale. If the purpose is business or investment, the red tape vanishes. You get the speed of hard money with the collateral you already live in. If you aren’t sure how much you can pull out, you can get a fast equity evaluation from our Scottsdale team to see your options.
Hard Money vs. HELOC: Choosing the Right Leverage Strategy
Choosing between a Home Equity Line of Credit (HELOC) and private capital is about matching the tool to the task. HELOCs are revolving lines meant for slow, long-term renovations where you draw cash over years. Hard money is a tactical strike. It’s a lump-sum bridge. When you leverage home equity hard money, you’re prioritizing the win over the interest rate. Most hard money structures use interest-only payments. This keeps your monthly burn low while you execute your business plan. You aren’t signing up for a thirty-year commitment. You’re building a bridge to a specific exit, like a property sale or a long-term refinance once the project is stabilized.
The biggest risk isn’t the cost of capital. It’s the cost of waiting. If a traditional bank takes sixty days to process your request, that “cheap” money becomes incredibly expensive if it costs you a massive profit on a time-sensitive flip. Understanding the difference between a home equity loan and a HELOC is vital, but in the fast-paced Arizona market, the real difference is the approval speed. Banks move at the speed of bureaucracy. Private lenders move at the speed of the deal.
When Speed Trumps Interest Rates
Arizona real estate investors often face an “Opportunity Cost.” In Phoenix or Scottsdale, off-market deals don’t wait for a bank’s multi-week underwriting process. Consider a land deal in Sedona. If a seller needs to close in ten days to avoid a tax lien, they’ll take a lower cash offer over a higher one tied to bank financing. By tapping your existing equity quickly, you secure the asset before a competitor even gets their paperwork started. You’re using your equity as a liquid weapon to win the auction or beat the out-of-state investor.
The ‘Bank Statement’ Advantage for Self-Employed
Entrepreneurs often have high cash flow but low taxable income due to deductions. This kills traditional equity loans instantly. Banks demand W-2s and perfect debt-to-income ratios. We don’t. By using Bank Statement Loans alongside hard money, you can prove your liquidity without the IRS headache. We look at your actual business deposits to verify your ability to handle the debt.
- Skip the tax return scrutiny.
- Use 12 or 24 months of deposits as proof of income.
- Get funded based on your business’s real-world performance.
Don’t let a bank’s rigid W-2 requirement stall your business expansion. Leverage what you’ve built to get where you’re going.
How to Secure Your Hard Money Equity Loan: A 5-Step Guide
Speed is the only metric that matters when you need to leverage home equity hard money. Forget the twenty-page bank applications that ask for your childhood pet’s name. Private lending is a sprint, not a marathon. You need a clear path from “equity on paper” to “cash in hand.” This five-step process cuts through the noise and puts you in the driver’s seat of your Arizona investment strategy. We prioritize the deal over the paperwork, ensuring your capital is ready when the opportunity is.
Step 1: The Initial Equity Audit
Start with a brutal look at your numbers. Pull your current mortgage statement and look at recent comps in Phoenix or Mesa. Don’t rely on automated valuation sites; look at what similar properties actually sold for in the last ninety days. This gives you your “Hard Money Value.” You must also check for any existing liens or judgments that could stall the process. Finally, prepare a “Use of Funds” statement. Tell us exactly how this cash will fuel your business or investment. It builds trust and proves you have a clear exit strategy.
Step 2: Securing the Term Sheet
Once the asset looks strong, you’ll receive a term sheet. A term sheet is a commitment to move at the speed of business. Look closely at the origination points and interest rates, but watch out for “junk fees” that some lenders hide in the fine print. A major advantage of our Cash Out Hard Money Loans is the lack of a prepayment penalty. Since these are bridge loans, you need the freedom to exit the debt the moment your project hits its milestone without being punished for your success.
Step 3: Rapid Appraisal and Title Search
Traditional banks wait weeks for a full interior appraisal. We don’t have that kind of time. Private lenders often use “drive-by” or desktop appraisals to verify property value in as little as forty-eight hours. While the value is being confirmed, we run a rapid title search. Arizona title companies are efficient, but you need a local partner who knows how to clear title clouds fast. Once underwriting confirms the asset’s safety, we move to the final stages.
The process concludes with underwriting and closing. We focus on the property’s condition rather than your tax returns. For the final signature, we use mobile notaries who meet you anywhere in Scottsdale or the surrounding Valley. You sign, the deed is recorded, and the funds are wired. The entire cycle typically happens in seven to twenty-one days. If you’re ready to stop waiting on bank red tape, you can start your rapid equity audit with our Scottsdale team today.
Why Applewood Funding is Arizona’s Equity Leverage Partner
Arizona real estate isn’t just a spreadsheet; it’s a living, breathing market. From the luxury estates in Scottsdale to the fast-moving fix-and-flips in Glendale, every zip code has its own rhythm. To leverage home equity hard money effectively, you need a partner who knows the Valley’s street corners, not just its credit scores. We aren’t a middleman or a broker who shops your deal around to strangers. We are a direct lender. When you talk to us, you’re talking to the source of the capital. This means we set the parameters, we evaluate the risk, and we sign the checks. We make the rules because we understand the local collateral better than any out-of-state institution.
We specialize in the “Hard Cases” that make traditional banks sweat. If you’re self-employed and your tax returns don’t reflect your actual cash flow, we look at your bank statements. If a past medical bill or a business setback dragged your credit score down, we look at your property’s value. We prioritize solutions over setbacks. Our goal is to find a way to say “yes” when the institutional system has already said “no.” The Applewood Promise is built on three pillars:
- Fast: We provide quotes in hours, not weeks.
- Honest: No hidden “junk fees” or last-minute surprises at the closing table.
- Solution-Oriented: We focus on how to fund the deal, not why we should reject it.
Meeting Joel McDaniel and the Applewood Team
Leading the charge is Joel McDaniel, a veteran who understands that reliability is just as important as speed. We provide the NMLS-backed security you expect from a professional firm (NMLS # 175371) combined with the agility of a private fund. We’ve funded Arizona’s most complex equity deals because we don’t hide behind call centers or offshore support. When you call Applewood, you get direct access to decision-makers. There’s no waiting for a committee in another time zone to approve your bridge loan. We make the call right here in Scottsdale, ensuring your business-purpose loan stays on track.
Ready to Get Liquid? Your Next Steps
Don’t let your next opportunity expire while you wait on a bank’s sixty-day process. You can request a quote in under two minutes through our streamlined portal. Within your first twenty-four hours with Applewood, you’ll have a clear understanding of your options and a realistic path to funding. We move at the speed of the Arizona market because we live here, work here, and invest here. Stop treating your equity like a dormant asset and start treating it like the capital engine it truly is. Leverage your Arizona home equity today with Applewood Funding and get the liquidity you need to win.
Stop Waiting and Start Winning in the Arizona Market
You’ve built massive wealth in your property. Don’t let a bank’s rigid underwriting keep that capital locked away. Whether you’re injecting cash into a Phoenix startup or securing a time-sensitive Scottsdale flip, the ability to leverage home equity hard money is your ultimate competitive advantage. You now have the roadmap to bypass the 60-day bank delay by prioritizing your property’s value over a credit score.
Applewood Funding stands as Arizona’s leader in owner-occupied hard money. We specialize in complex transitions that traditional lenders simply won’t touch. We don’t require W-2s or tax returns to see the potential in your next move. Our team focuses on speed and transparency, providing funding in as little as 7 days so you can act while the opportunity is hot. Your next big business move is just one valuation away.
Unlock Your Arizona Equity Now – Get Your Hard Money Quote
Your property is ready to work for you. Let’s make it happen.
Frequently Asked Questions
Can I get a hard money loan on my primary residence in Arizona?
Yes, you can secure a hard money loan on your primary residence through Applewood Funding. While most out-of-state private lenders avoid owner-occupied properties due to complex federal regulations, we specialize in this niche for business-purpose loans. Whether you live in Phoenix or Scottsdale, you can use your home’s value to fund an investment or business expansion. We prioritize the asset’s equity over the property’s occupancy status to help you move fast.
What is the maximum LTV for a hard money home equity loan?
Arizona lenders generally cap the Loan-to-Value (LTV) ratio at 60% to 70% for these transactions. This conservative limit ensures a “protective equity” cushion for the lender while providing you with significant liquidity. If your Scottsdale home is worth $500,000 and you have a $200,000 balance, you could potentially access another $100,000 to $150,000. It’s the most reliable way to leverage home equity hard money for high-speed business opportunities.
Do I need a high credit score to leverage my equity with hard money?
No, you don’t need a high credit score because hard money is primarily asset-based. We focus on the “skin in the game” and the property’s current market value rather than your FICO history. While a traditional bank might reject a 580 score, we look for enough equity to secure the deal. This flexibility makes it an ideal solution for self-employed entrepreneurs in Mesa or Tempe who have strong assets but complex credit profiles.
How fast can I get cash from a hard money equity loan?
You can typically receive your funds in 7 to 21 business days after providing complete documentation. This is significantly faster than the 45 to 60 days required by traditional banks for a standard HELOC. Because we are a direct lender, we make the decisions in-house without waiting for a distant committee. In some urgent cases involving clear titles in the Valley, we’ve seen deals move even faster to meet tight deadlines.
What are the typical terms for a hard money cash-out refinance?
Typical terms include a 1 to 2 year interest-only period or a 3 to 5 year term with a 30-year amortization. These are short-term bridge solutions designed to get you to a specific exit point, like a property sale or a long-term bank refinance. Interest rates are higher than traditional mortgages, but the trade-off is the extreme speed and simplified approval process. It’s a strategic way to leverage home equity hard money for growth.
Can I use hard money to pay off back taxes or stop foreclosure?
Yes, you can use a hard money equity loan to pay off IRS liens, delinquent property taxes, or to stop an active foreclosure. Private capital is often the only way to rescue a property when traditional banks refuse to lend due to legal clouds. By tapping into your existing equity, you can clear the debt and stabilize your financial situation. This provides the breathing room needed to eventually sell the property or transition to conventional financing.
What happens if I can’t pay back the hard money loan?
If you can’t repay the loan, the lender may initiate foreclosure proceedings to recover the capital using the property as collateral. This is why having a rock-solid exit strategy is mandatory for every borrower we work with in Arizona. Since these are short-term bridge loans, you should have a clear plan to either sell the asset or refinance into a long-term mortgage before the term ends. We work with you to ensure the plan is realistic.
Is there a prepayment penalty on Applewood Funding loans?
Applewood Funding typically offers loans with no prepayment penalties, giving you the freedom to exit the debt early without extra costs. This is a massive advantage for investors who might complete a project faster than expected. If you flip a house in Peoria or Glendale in six months, you can pay off the balance immediately. You shouldn’t be punished for your success or for moving faster than your original business plan anticipated.