Mortgage for Self Employed Borrowers: How to Secure Funding in 2026
September 16, 2026Bank Statement Mortgage No Tax Returns: The 2026 Arizona Guide
Why should your tax write-offs stand between you and your dream home in Scottsdale? You’ve spent years building a successful business in Arizona, yet traditional lenders treat your tax returns like a deal breaker. It’s a common trap. You maximize your deductions to grow your company, and the big banks reward your hard work with a rejection letter. It’s time to skip the red tape and secure a bank statement mortgage no tax returns required. The frustration is real, especially when the Phoenix market is moving faster than ever. You shouldn’t have to choose between a lower tax bill and a new front door.
We agree that your success deserves better than a “no.” That’s why we’re showing you a faster, smarter way to buy. This 2026 guide reveals how to bypass the traditional lending hurdles and secure the keys to your property. At Applewood Funding, we prioritize your actual cash flow over IRS paperwork. You’ll discover exactly how the process works for self-employed professionals, what documents you actually need, and how to get funded in days. Let’s clear the path to your next home in cities like Sedona or Mesa without the typical bureaucratic headaches. Your bank statements tell the real story of your success. It’s time you had a lender who listens.
Key Takeaways
- Stop letting tax write-offs block your homeownership goals and qualify using gross deposits with a bank statement mortgage no tax returns required.
- Leverage 12 or 24 months of bank statements to prove your real purchasing power without the need for complex IRS forms.
- Protect your business privacy and accelerate your closing date by removing the manual underwriting delays common at big banks.
- Prepare for a seamless application by organizing consecutive statements and verifying two years of self-employment in your field.
- Gain a competitive edge in fast-moving Arizona markets like Scottsdale by working with local experts who value equity over red tape.
What is a Bank Statement Mortgage with No Tax Returns?
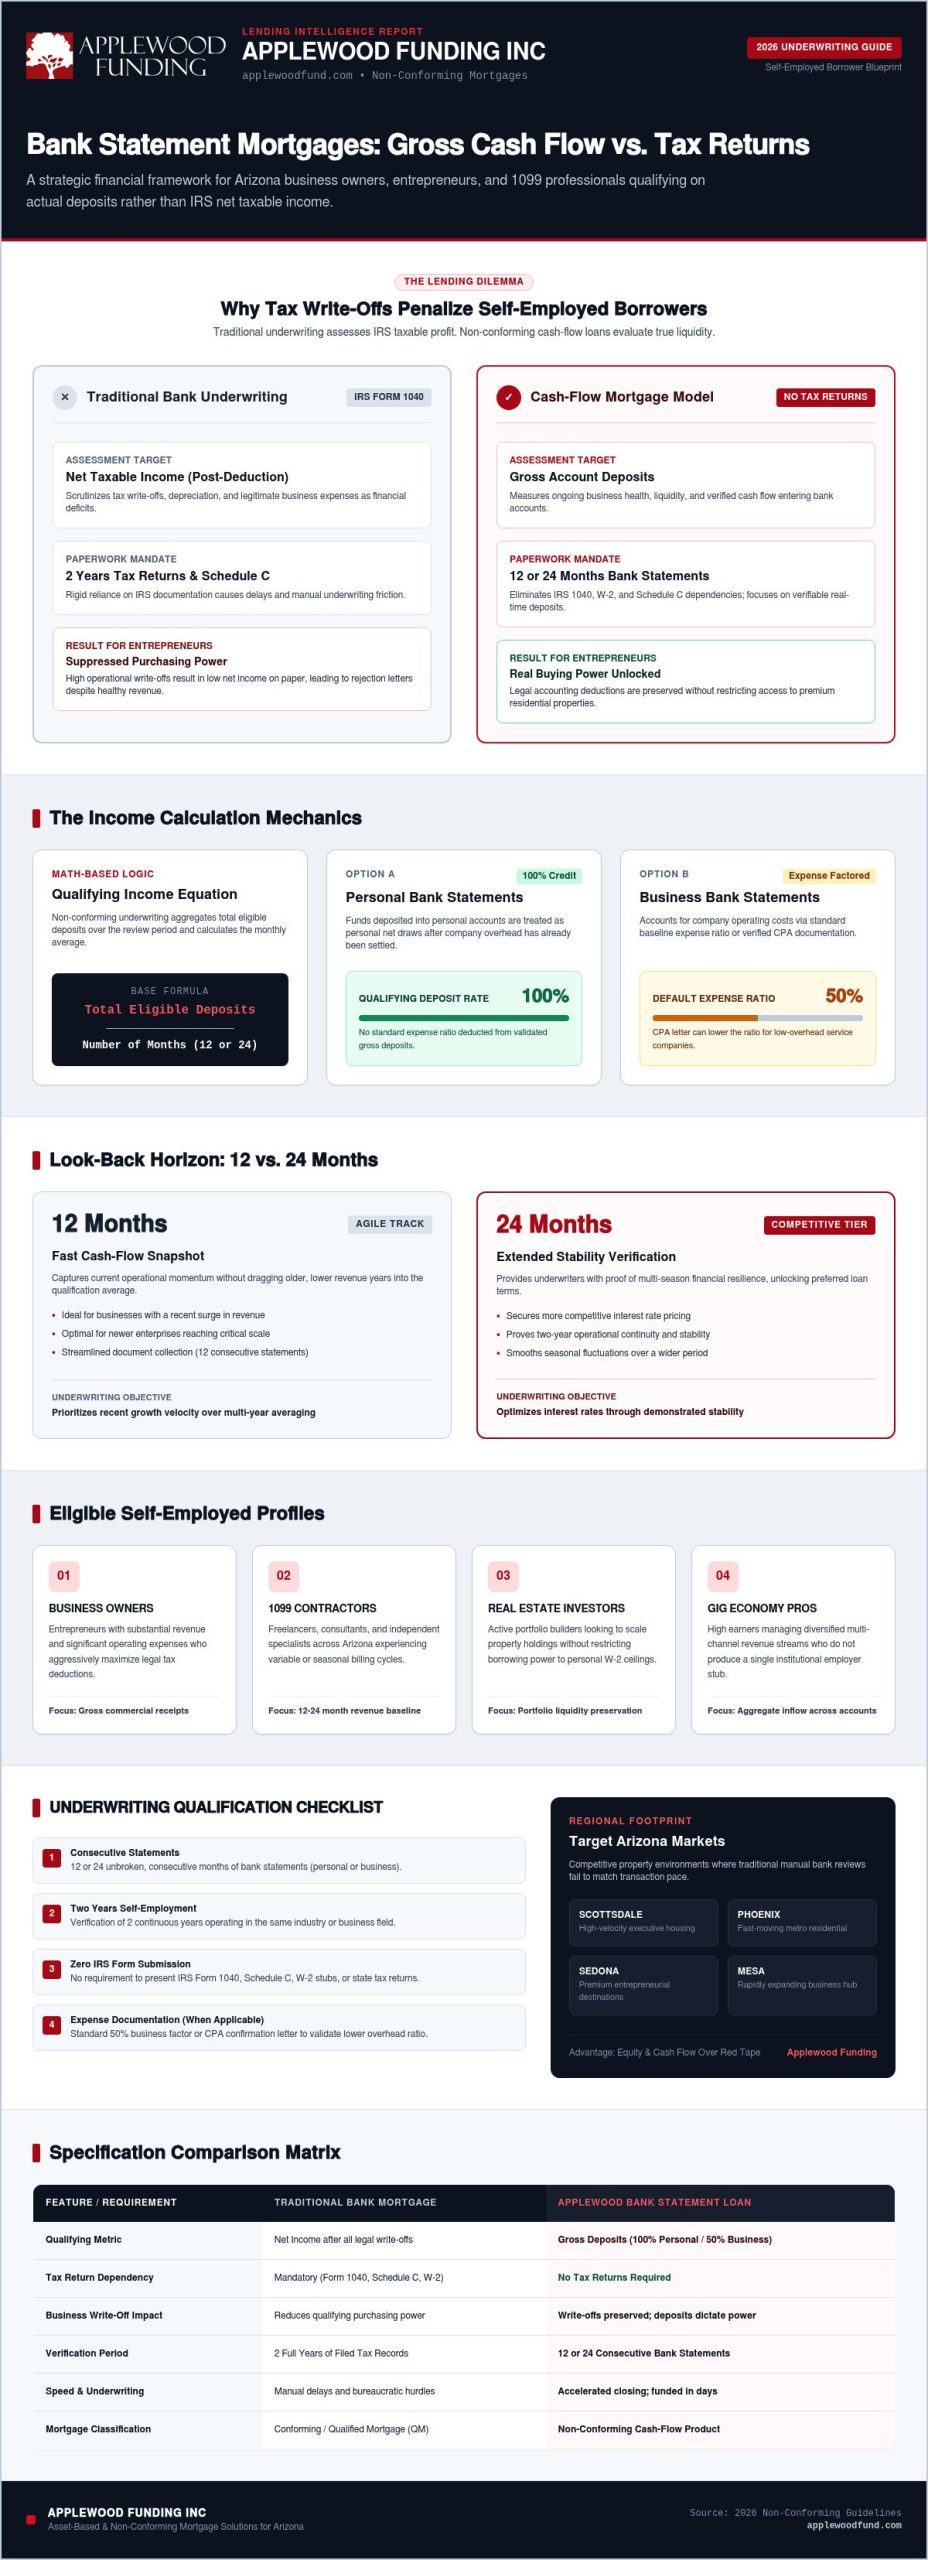
A bank statement loan is a cash-flow based mortgage solution for the modern entrepreneur. It is specifically designed for the Arizona business owner who generates significant revenue but doesn’t fit the rigid profile of a traditional W-2 employee. Instead of scrutinizing your net income after all your legal deductions, we focus on your gross deposits. This creates a total bypass of IRS Form 1040 and Schedule C reviews. It is a type of non-conforming mortgages, which provide the flexibility that high-achieving entrepreneurs need to secure property in competitive markets like Phoenix or Scottsdale.
Securing a bank statement mortgage no tax returns means your business success isn’t punished by your savvy accounting. Traditional lenders look at your tax returns and see a low net income; we look at your bank statements and see a thriving business. If you have high operational expenses that lower your taxable income, this product is your ticket to homeownership. It’s about looking at the money you actually have, not just what the IRS sees at the end of the year. We prioritize your actual buying power over outdated paperwork.
The Death of the W-2 Requirement
Traditional banks are addicted to the simplicity of a W-2. They struggle with the natural volatility of self-employment. When you invest in your business, you create “paper losses” through depreciation and expenses. To a big bank, that paper loss makes you look like a risk. To us, it looks like growth. The lending world changed in 2026. We’ve shifted toward asset-based and cash-flow lending because your monthly deposits are a real-time indicator of your ability to pay. Choosing a bank statement mortgage no tax returns allows you to bypass these manual underwriting traps and close on your home faster.
Who Qualifies for No-Tax-Return Loans?
This program isn’t a niche product for a few; it’s a vital tool for the backbone of the Arizona economy. If your income doesn’t come from a standard salary, you likely qualify. This includes:
- Business Owners: Entrepreneurs with high overhead who maximize their tax deductions.
- Freelancers and 1099 Contractors: Professionals in Scottsdale or Sedona with fluctuating monthly revenues.
- Real Estate Investors: Buyers looking to scale their portfolios without tying up personal income.
- Gig Economy Pros: High-earners managing multiple revenue streams across various platforms.
At Applewood Funding, we believe your bank statement is the most honest financial document you own. We use it to tell the true story of your success while the big banks are still stuck reading your tax returns. Don’t let your accountant’s hard work stop you from buying a home.
The Mechanics: How 12 and 24-Month Bank Statement Loans Work
Traditional banks want a history lesson; we want a snapshot of your current success. While these products sit outside standard CFPB Qualified Mortgage criteria, they follow a clear, math-based logic. The process is straightforward. We add up your total deposits over a 12 or 24-month period and divide by the number of months to find your qualifying income. Securing a bank statement mortgage no tax returns doesn’t mean the rules are gone. It means the rules finally make sense for Arizona business owners who value speed over bureaucracy.
Stability matters to underwriters. A 24-month look-back often secures a more competitive interest rate because it proves long-term revenue consistency. If your business is newer or experiencing a recent surge, a 12-month “quick” look might be the better path. Both options allow you to bypass the tax return trap. We focus on the cash flowing into your accounts today, not the deductions you took two years ago.
Business vs. Personal Statements
The documentation path you choose changes your qualifying power. If you provide personal bank statements, we typically count 100% of those deposits as income. This is because the money hitting your personal account has usually already been cleared of business overhead. Business statements are handled differently. We apply an “Expense Ratio,” often a flat 50%, to account for the costs of running your company. If your business has exceptionally low overhead, a CPA letter can often lower that ratio, allowing for a higher loan amount. Choose the path that reflects your true wealth.
Calculating Your Qualifying Income
The formula is transparent: (Total Deposits multiplied by Ownership Percentage) minus the Expense Ratio equals your Monthly Income. No hidden IRS formulas. No surprises. You need to prepare for the scrutiny of large, one-time deposits. Transfers between your own accounts won’t count as revenue. We look for legitimate business income from clients and customers. Consistency is king. While “lumpy” revenue is common for freelancers, a steady stream of deposits makes for a stronger application.
Ready to see how your deposits translate into a mortgage? You can connect with an Arizona mortgage specialist to run your specific numbers. We prioritize equity and real-world cash flow to get you into your Scottsdale or Phoenix home without the wait.
Strategic Advantages: Why Skip Tax Returns in 2026?
Choosing a bank statement mortgage no tax returns isn’t just about avoiding a headache. It’s a calculated strategic move for the modern Arizona entrepreneur. Your tax returns are a private roadmap of your business strategy, proprietary data, and investment choices. Why hand that over to a bank underwriter who doesn’t understand your industry? By skipping the 1040s, you maintain your financial privacy while focusing on the one metric that actually matters: your liquidity. We look at the cash you have on hand today, not the historical data the IRS cares about.
Flexibility is the second major win. Traditional lending is a rigid box. If you don’t fit, you’re out. But Arizona’s economy is built on people who think outside that box. Using your actual business deposits allows you to move with the agility of a cash buyer. Speed is the new currency in the Scottsdale and Phoenix real estate markets. If you’re waiting for a big bank to finish its three-month “manual review,” you’ve already lost the house to a faster bidder. We prioritize your ability to act now.
Speed Over Red Tape
Big banks are built for the 1950s. They want to see every receipt and every schedule. At Applewood Funding, we close loans while those institutional lenders are still reading page one of your tax return. We leverage a “Hard Money” mindset that focuses on equity and cash flow rather than bureaucratic check-boxes. This aggressive approach lets you bypass the standard waiting periods that kill deals. You can learn more about how we outpace traditional lenders in our guide on Hard Money vs Conventional Loans: Speed Over Red Tape. We’re your fast-acting ally in a high-speed market.
Maximizing Your Purchasing Power
The math is simple but powerful. Traditional banks qualify you based on your taxable income. If you have $200,000 in annual business deposits but your savvy accounting shows only $40,000 in taxable income, a big bank will offer you a loan for a starter condo. We qualify you based on that $200,000. This shift in perspective can triple your purchasing power overnight. Understanding the specific bank statement loan requirements helps you see why this is the superior choice for growth-minded professionals. You can protect your business capital and still secure the luxury primary residence you’ve earned. Don’t let your tax deductions limit your lifestyle.
Qualification Checklist: What Arizona Borrowers Need to Apply
Stop wasting time with bank appointments that go nowhere. You have the revenue. You have the equity. Now you just need the right checklist. Getting qualified for a bank statement mortgage no tax returns is simpler than the traditional route because it cuts out the noise. We don’t care about your tax deductions. We care about your business’s ability to generate cash right now. The most critical requirement is providing 12 months of consecutive bank statements. There can’t be any missing months. We look for a steady flow of business activity that shows your company is healthy and active in the current Arizona market.
You also need to show you’ve been in the game for at least two years. This proves your business isn’t a flash in the pan. We verify this through a business license or a simple letter from your CPA verifying your ownership. Credit scores also work differently here. While Fannie Mae or FHA lenders might reject you for a minor dip in your score, bank statement loans offer much more flexibility. We prioritize your equity and cash flow over a rigid number on a screen. If you have the down payment and the deposits, we have a path for you.
Documenting Your Business Success
Gather your LLC or corporate organizational documents early. If you’re a freelancer, having your 1099s ready can help build a stronger case for your income consistency. What if your spouse has a traditional job? We can handle co-borrowers with W-2 income alongside your bank statement qualification. It’s a hybrid approach that maximizes your total household buying power. For a deeper look at these alternative paths, check out our Self Employed Home Loan No W2: Your 2026 Guide. We make the documentation fit your life, not the other way around.
Property Requirements in Arizona
Arizona properties are unique, and your lender should understand that. From high-rise condos in Phoenix to short-term rental powerhouses in Sedona, we know the local landscape. National lenders often shy away from “non-warrantable” condos or properties with unique zoning. We don’t. Your property type may influence your down payment, but we focus on the equity you’re bringing to the table. If you need a primary residence fast and don’t want to wait for traditional underwriting, our Owner Occupied Hard Money Loans provide the speed big banks lack. We fund the home you want, where you want it.
Ready to see if your bank statements pass the test? You can talk to a local Arizona mortgage expert today and get a clear answer on your purchasing power. Don’t let another Scottsdale dream home slip away while you’re hunting for old tax returns.
Securing Your Arizona Home with Applewood Funding
Don’t settle for a national lender who thinks Scottsdale is just a vacation spot. We live and work here. Applewood Funding Inc understands the local market dynamics better than any big bank. We know that a bank statement mortgage no tax returns is often the only way a high-performing Arizona entrepreneur can compete. Our process is fast. It is direct. It is driven by your equity and cash flow, not a government-mandated checklist. We look at your real-world success to provide real-world funding.
We believe in customization. Every business is different, so every loan should be too. From 12-month bank statement reviews to rare owner-occupied hard money options, we build solutions around your specific financial profile. Taking the first step shouldn’t be a headache. We’ve removed the layers of bureaucracy to give you a clear, honest assessment of your options in record time. You deserve a lender that moves at the speed of your business.
Expertise You Can Trust
Applewood Funding is managed by Joel McDaniel. His local Arizona knowledge has been the foundation of our company since its inception. We specialize in those “outside the box” scenarios that make big banks nervous. We focus on your equity and the strength of your cash flow. Whether you are buying in Sedona or Phoenix, we understand the property values and the local nuances that national call centers miss. Learn more about our specialized approach in our guide on Mortgage for Self Employed Borrowers: How to Secure Funding in 2026. We don’t just process loans; we find ways to say yes.
Get Started Today
We value your time because we know speed is your greatest advantage. That’s why we offer a 24-hour turnaround on initial bank statement reviews. You won’t wait weeks for an answer. Submit your statements securely and get a rapid quote for a bank statement mortgage no tax returns that reflects your true purchasing power. Our team is ready to move as fast as the Phoenix market demands. Stop guessing what you can afford and start shopping with confidence. Get your Arizona bank statement loan quote from Applewood Funding Inc today!
Take Control of Your Arizona Homeownership Goals
Your business success shouldn’t be a barrier to buying a home. You now have the blueprint to bypass traditional red tape and leverage your actual revenue. By focusing on 12 or 24 months of deposits, you can secure a bank statement mortgage no tax returns and move with the speed of a cash buyer. This is about more than just a loan; it’s about recognizing your real-world purchasing power. We prioritize your results over your tax deductions.
Applewood Funding is the fast-acting ally you need in a competitive market. Led by Joel McDaniel (NMLS 175371), we specialize in Arizona owner-occupied hard money and alternative solutions that big banks simply won’t touch. We deliver fast closing times for self-employed borrowers because we value your equity over institutional bureaucracy. Don’t let another dream home in Sedona or Phoenix slip away while you wait for a traditional underwriter to catch up. It’s time to use a lender that understands your hustle.
Secure Your Arizona Home Loan Without Tax Returns—Start Here
Your next front door is closer than you think. Let’s get to work and make it happen today.
Frequently Asked Questions
Can I really get a mortgage without any tax returns?
Yes, you can secure a bank statement mortgage no tax returns by using your gross deposits as proof of income. This program is specifically designed for Arizona entrepreneurs who have high tax write-offs that lower their net income on paper. Instead of reviewing your IRS filings, we look at the actual cash flowing into your accounts. This allows you to qualify based on your business’s real-world success rather than an outdated tax form.
What is the minimum credit score for a bank statement loan in Arizona?
Flexibility is the core of our lending philosophy. While traditional lenders often require a 620 to 640 score, bank statement loans in cities like Phoenix and Mesa can often be secured with scores in the low 600s. At Applewood Funding, we prioritize your down payment and equity over a rigid credit score. If you have significant skin in the game and strong deposits, we can usually find a path to approval that big banks ignore.
Do bank statement loans have higher interest rates than traditional loans?
Typically, interest rates for bank statement products are slightly higher than standard Fannie Mae or Freddie Mac loans. This reflects the alternative nature of the documentation and the increased risk the lender assumes by skipping tax returns. However, most Arizona borrowers find the trade-off worth it. The ability to secure a home in a competitive market like Scottsdale without months of red tape often outweighs the incremental difference in the monthly payment.
Can I use business bank statements if I am only a 50% owner?
Yes, you can use business statements even if you aren’t the sole owner. We simply apply your ownership percentage to the total qualifying deposits. For example, if you own 50% of a Phoenix-based LLC, we will count half of the eligible business revenue toward your personal income calculation. You will just need to provide an operating agreement or a CPA letter to verify your specific stake in the company before we finalize the numbers.
How many months of bank statements do I need for a 2026 mortgage?
Most programs in 2026 require either 12 or 24 months of consecutive bank statements. A 12-month look-back is perfect for businesses that have seen recent growth or a surge in revenue. If your income has been stable for a longer period, providing 24 months of statements often helps you secure a lower interest rate. We use these documents to calculate a monthly average that proves you have the consistent cash flow to handle the mortgage.
Is a bank statement loan considered a ‘hard money’ loan?
No, a bank statement loan is technically a Non-QM (Non-Qualified Mortgage) product, not hard money. While both offer more speed than a traditional bank, bank statement loans are based on cash flow rather than just the property’s equity. However, Applewood Funding specializes in both. If you don’t qualify for a bank statement loan, we can often pivot to an owner-occupied hard money solution to ensure you don’t lose your dream property in Sedona.
Can I get a bank statement loan for a primary residence in Scottsdale?
Yes, you can absolutely use a bank statement mortgage no tax returns for your primary residence. Unlike many private lenders who only fund investment properties, Applewood Funding offers specialized owner-occupied solutions throughout Scottsdale and the greater Phoenix area. We understand that self-employed professionals need a place to live, too. Whether you’re buying a luxury estate or a family home, we use your business success to help you move into your new primary residence.
What happens if my bank statements show large, irregular deposits?
Irregular or large one-time deposits are common for Arizona contractors and freelancers, but they require a clear explanation. Underwriters look for “sourced” income, meaning you may need to provide a contract or an invoice to prove the deposit was business-related. Transfers between your own accounts are generally excluded from the income calculation. We focus on the consistency of your client-based revenue to ensure your monthly income average is accurate and sustainable for the long term.