Bank Statement Mortgage No Tax Returns: The 2026 Arizona Guide
September 17, 2026Cash Out Hard Money Loans: Unlock Your Arizona Property Equity in 2026
Why is your property equity locked in a vault while you wait for a bank’s slow-motion approval process? It’s a common trap. You have the value, but you can’t touch it because of strict credit scores or complicated debt-to-income ratios. We understand the frustration of watching a prime Arizona investment opportunity vanish because of institutional red tape. Your real estate should be your greatest tool, not a frozen asset. A cash out hard money loan allows you to bypass the bureaucracy and put your equity to work immediately.
In this guide, you’ll learn how to leverage your property for fast capital even when traditional lenders turn you away. We’ll show you why equity-based approvals are the fastest path to funding in 2026. We will cover current LTV limits for Scottsdale and Phoenix properties, the benefits of skipping the DTI hurdle, and how to structure a clear short-term exit strategy. It’s time to stop waiting for permission and start moving at the speed of the market. Let’s unlock your capital today.
Key Takeaways
- Slash your waiting time from months to days by securing capital in as little as 24 to 72 hours.
- Learn how a cash out hard money loan prioritizes your property’s equity over strict credit scores or debt-to-income ratios.
- Discover how to turn trapped equity into a strategic tool for funding new fix-and-flip projects or scaling your business.
- Understand the critical 2026 LTV limits for Arizona properties to ensure your loan application is positioned for immediate approval.
- Gain a competitive edge by working with local Arizona experts who offer rare owner-occupied hard money solutions.
What is a Cash Out Hard Money Loan and How Does It Work?
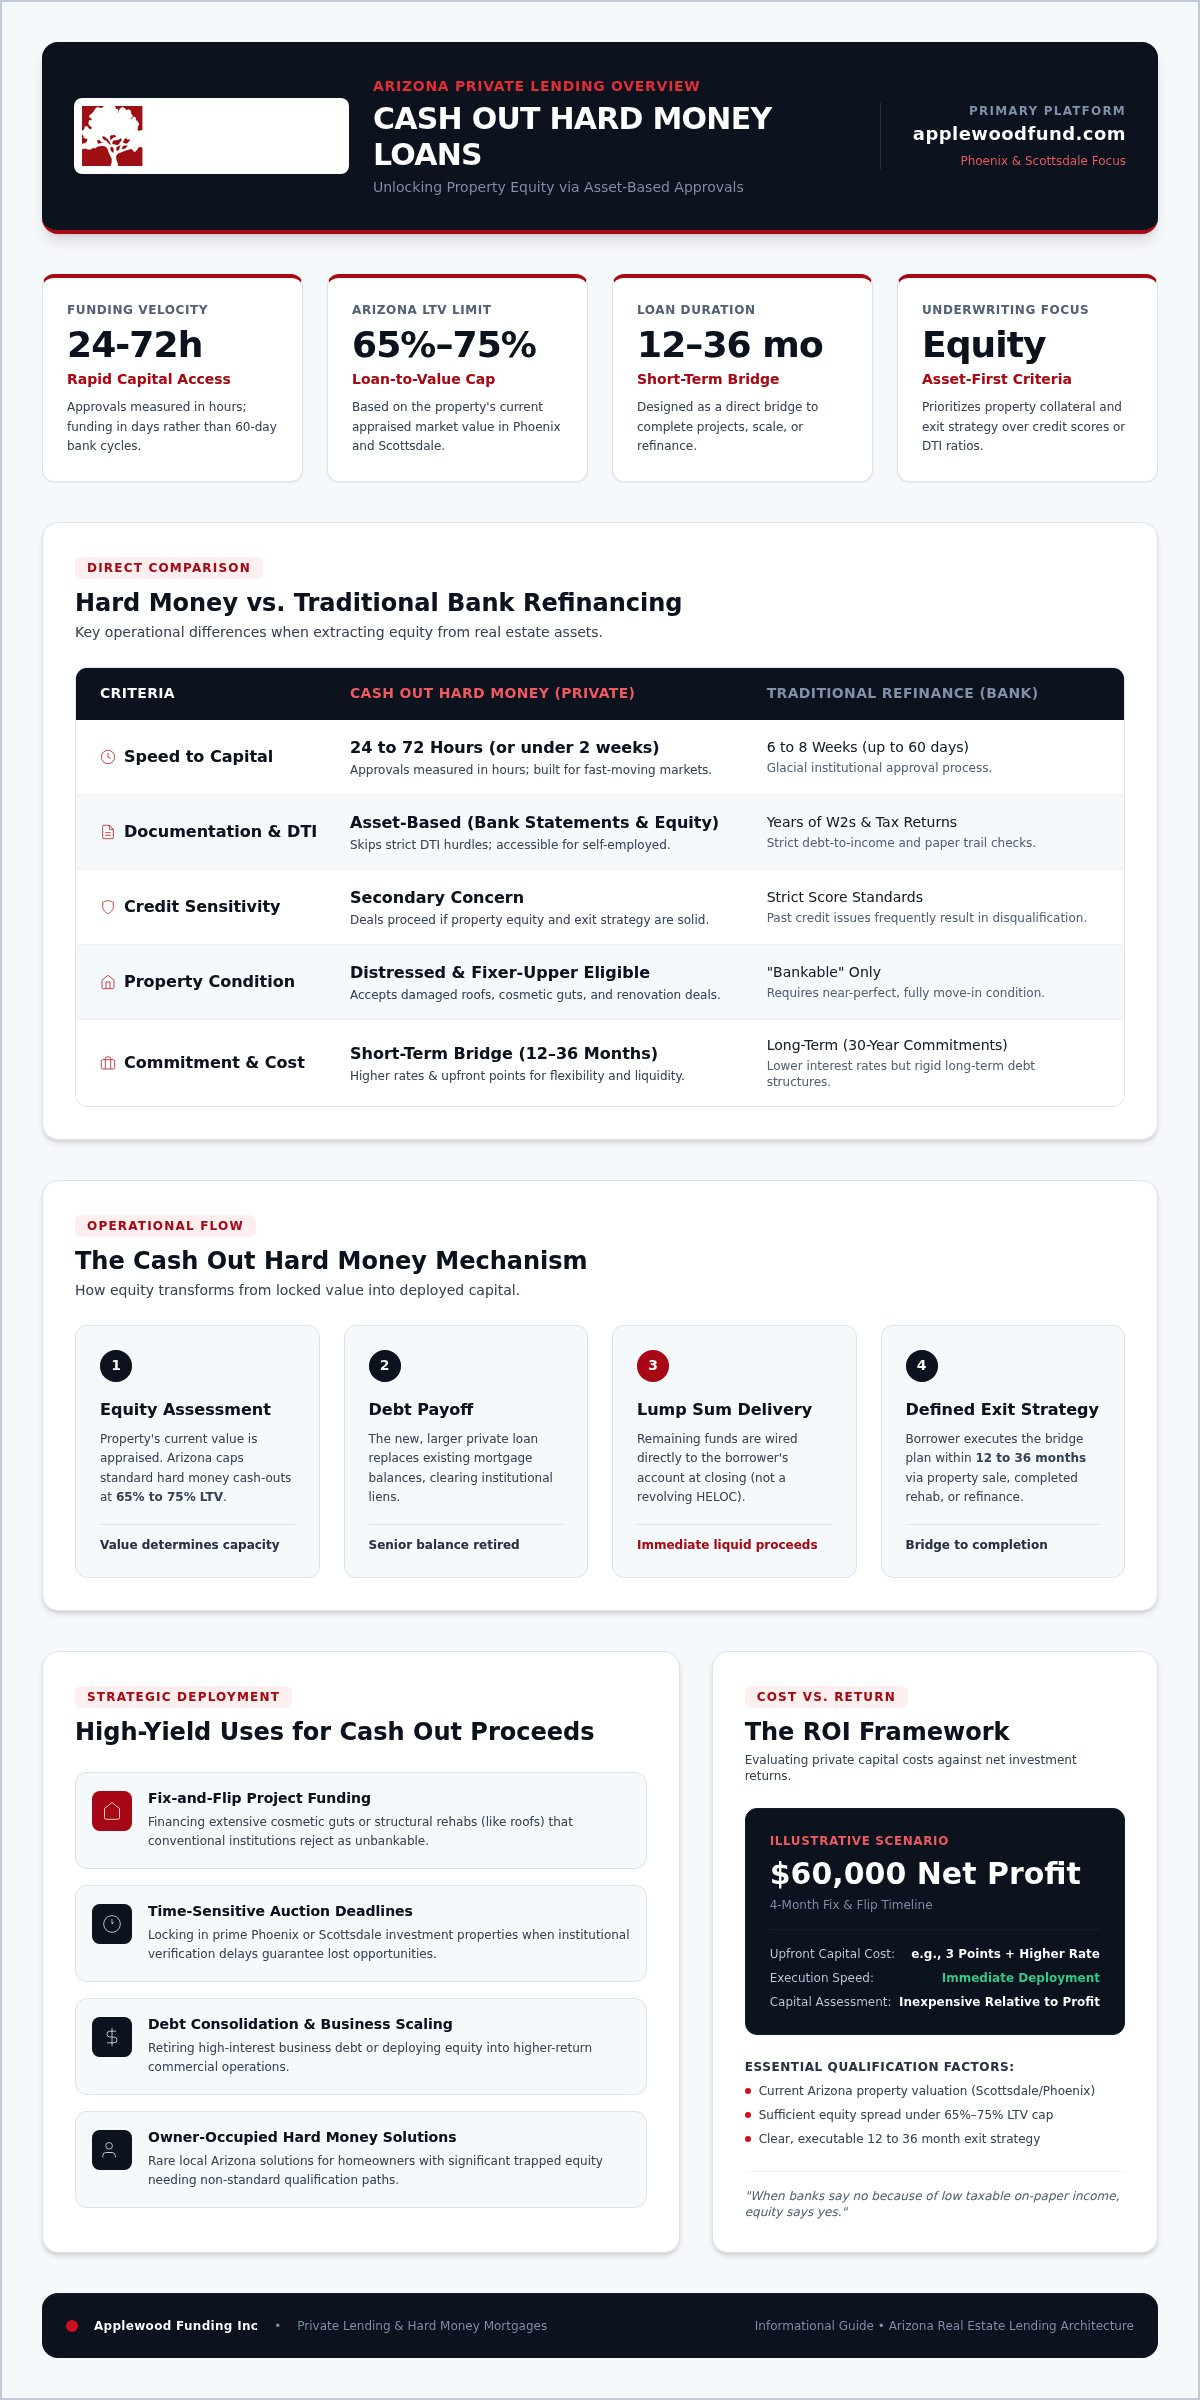
A cash out hard money loan is a strategic financial tool built for speed and liquidity. It’s an asset-based loan where your property’s equity serves as the primary collateral. Instead of waiting for a bank to scrutinize your personal history, you leverage the value you’ve already built in real estate. The mechanism is straightforward. You refinance your existing mortgage into a new, larger loan from a private lender. You pay off the old debt and pocket the difference in a single lump sum. This isn’t a HELOC. You don’t get a revolving line of credit; you get immediate capital delivered to your bank account at closing.
Private lenders prioritize your exit strategy over your past credit mistakes. They want to know your plan for repayment. Whether you intend to sell the property, finish a renovation, or eventually refinance into a long-term bank loan, a clear path out is essential. At Applewood Funding Inc, we focus on the deal’s potential rather than institutional red tape. We look at what the property is worth today and how that value can solve your immediate capital needs.
The Mechanics of Equity-Based Lending
Equity is the engine of every deal. Lenders use a Loan-to-Value (LTV) ratio to decide your maximum payout. In the Arizona market, hard money loans typically cap at 65% to 75% of the property’s current value. Because the asset secures the transaction, your credit score becomes a secondary concern. If the equity is there, the deal is usually there too. This asset-focused approach allows for incredible speed. While a bank might take 60 days to verify your tax returns, a private lender can often fund your project in less than two weeks. Speed is the ultimate advantage when an opportunity won’t wait.
Hard Money vs. Conventional Cash-Out
Conventional loans are a marathon of paperwork. They demand years of W2s, tax returns, and perfect debt-to-income ratios. Hard money offers a shortcut for self-employed borrowers or those with unique financial situations. The trade-off is the cost of capital. You’ll pay higher interest rates for this level of flexibility and rapid execution. These aren’t 30-year commitments. Most cash-out hard money agreements last between 12 and 36 months. Think of it as a bridge. It’s a short-term solution designed to get you from your current bottleneck to your next big win without the bank’s permission.
Hard Money vs. Traditional Refinancing: A Strategic Comparison
Banks move at a glacial pace. Traditional refinancing is a marathon of bureaucracy that often lasts six to eight weeks. For an investor in a fast-moving market like Phoenix or Scottsdale, that delay is a deal-killer. A cash out hard money loan operates on a different timeline. We measure approvals in hours and funding in days. You can often secure capital in 24 to 72 hours, giving you the agility to act while others are still filling out forms.
The documentation gap is just as wide. Banks demand a mountain of W2s, years of tax returns, and perfect debt-to-income ratios. If you’re self-employed, this process is an uphill battle. Private lenders prioritize bank statements and property equity over your personal paper trail. This focus on assets is why CFPB research on cash-out refinancing highlights the shifting dynamics for borrowers in high-interest environments. When banks say no because of a low taxable income, equity says yes.
Property condition also dictates your options. Traditional lenders want “bankable” assets, meaning properties in near-perfect condition. If your Arizona property needs a new roof or a full cosmetic gut, a bank won’t touch it. Hard money lenders specialize in these distressed scenarios. We see the potential value, not just the current damage. You’ll pay higher points and closing costs upfront, but you gain the liquidity needed to transform the asset.
When to Choose Hard Money Over a Bank
Choose speed when time is your enemy. If a time-sensitive business opportunity arises or an auction deadline is looming, waiting for a bank is a guaranteed loss. Hard money is the go-to solution for properties that need significant rehab before they can qualify for traditional financing. It’s also the ideal path for high-net-worth borrowers who have massive equity but don’t fit the rigid “on-paper” income requirements of institutional lenders. If you need to move fast, talk to a local Arizona expert about your equity options.
The Cost-Benefit Analysis of Private Capital
It’s about ROI, not just the interest rate. If paying 3 points and a higher rate allows you to secure a property flip that nets a $60,000 profit in four months, that capital is incredibly cheap. You can also use these funds to consolidate high-interest business debt or bridge a gap while waiting for a long-term exit. Speed can save a deal worth significantly more than the total interest cost of a short-term bridge loan.
Strategic Uses for Your Hard Money Cash Out Proceeds
Your property equity is dormant capital. It sits in your walls while you wait for the perfect moment to grow. A cash out hard money loan turns that static value into immediate, actionable liquidity. Whether you’re a seasoned investor or a local business owner, this capital acts as a catalyst for your next move. You aren’t just borrowing money; you’re buying speed and market advantage. Traditional banks won’t let you tap into equity for aggressive growth, but private capital thrives on it.
- Funding Fix-and-Flip Projects: Use the equity in a stabilized asset to fund the acquisition and renovation of your next win.
- Business Expansion: Secure liquidity for inventory spikes, new equipment, or bridging payroll during rapid growth phases.
- Property Improvements: Finance a major remodel or a structural addition that increases your asset’s value before a planned sale.
- Bridge to Permanent Financing: Get the cash you need today while you wait for a traditional bank’s 60 day approval process to conclude.
Leveraging Equity for Real Estate Investors
Scaling a rental portfolio in competitive Arizona markets like Mesa or Tempe requires a significant war chest. You can’t always wait for a property to sell to fund your next purchase. By extracting equity from your existing holdings, you can move on new listings instantly. This strategy is also vital for covering unexpected gaps in construction or land development projects. If your project hits a snag, your equity is your safety net. Learn more in our Fix and Flip Loans: Arizona Investor Guide.
Rare Opportunity: Owner-Occupied Cash Out
Most hard money lenders strictly avoid primary residences. They find the regulations too complex and the hurdles too high. Applewood Funding is different. We are one of the few Arizona lenders willing to help homeowners access equity in their primary residence. Life happens. Emergency financial needs don’t wait for your credit score to improve or for a bank to finish their audit. If you have significant equity, you have a solution. We provide a clear path to liquidity when traditional institutions decline your application. Read more about Owner Occupied Hard Money: Fast Funding and how it can save your financial timeline.
Qualifying for a Cash Out Hard Money Loan in Arizona
Qualifying for a cash out hard money loan in Arizona is a clinical process. It isn’t personal. It’s about the asset. While banks obsess over your debt-to-income ratio, we focus on the numbers that actually matter: equity and exit. If the value is in the property, we can move. We don’t want to see a mountain of paperwork; we want to see a solid deal with a clear path to success.
The process follows four specific steps. Step 1 is the Property Valuation. We require a recent appraisal or a Broker Price Opinion (BPO) to establish a baseline. We need to know what the market says your property is worth today, not what it was worth three years ago. Step 2 is the Equity Assessment. We calculate your Loan-to-Value (LTV) ratio. Most Arizona equity extractions in 2026 cap between 65% and 75% LTV. This protective layer ensures the deal is secure. Step 3 is your Exit Strategy. You must have a plan to repay the loan, usually through a property sale or a future refinance. Finally, Step 4 is the Application. We don’t need your life story. Just give us your bank statements and property info to get started.
Arizona-Specific Lending Requirements
Market dynamics vary across the state. A fix-and-flip in Phoenix is a different play than a luxury equity extraction in Scottsdale or a vacation rental project in Sedona. We understand these local nuances. For self-employed borrowers, we bypass the tax return headache entirely. We look at your actual cash flow. Our Bank Statement Loans: Ultimate Guide explains how we use your real-world income to fund your next big move without the traditional bank delays.
Overcoming Common Qualifying Hurdles
A low credit score or a recent bankruptcy shouldn’t be a financial death sentence. Banks see a “no.” We see an opportunity. Private lenders use an “Equity First” approach where the property’s value is the primary driver of the approval process. If you have significant equity, your credit score becomes a secondary detail. We also offer proof of income alternatives. Bank statements often provide a much more accurate picture of a business owner’s health than a W2 ever could. We focus on your ability to execute your plan, not your past credit history.
Don’t let institutional red tape freeze your capital. Contact our Arizona team today to see how much equity you can unlock in days, not months.
Why Arizona Borrowers Choose Applewood Funding
Stop waiting for a corporate committee to decide your financial future. At Applewood Funding, we cut through the noise. When you partner with us, you get direct access to Joel McDaniel and a local Phoenix-based team that lives and breathes Arizona real estate. We don’t hide behind layers of middle management. You talk directly to the decision-makers who understand the urgency of your capital needs. This direct approach is why we can move from application to funding in record time while traditional banks are still debating your credit score.
We pride ourselves on absolute transparency. You won’t find any hidden fees or “bait and switch” tactics on your interest rates here. We provide clear, honest terms from the very first conversation. One of our most significant advantages is our specialized focus on owner-occupied properties. Most private lenders avoid these due to regulatory complexity, but we’ve mastered the process to help homeowners access their equity when it matters most. A cash out hard money loan through Applewood is a high-speed tool for those who value results over bureaucracy.
The Applewood Advantage: Local Expertise
Arizona is our home. We understand the specific values of properties from the historic neighborhoods of Tucson to the booming tech corridors of Phoenix and the luxury markets of Scottsdale. We don’t just look at a spreadsheet; we look at the dirt. This local perspective allows us to craft tailored solutions for complex scenarios that institutional lenders won’t even consider. Whether it’s a unique land deal in Sedona or a self-employed borrower in Glendale with trapped equity, we find a way to fund. For a full breakdown of the trade-offs involved in private capital, check our strategic guide on Hard Money Loan Pros and Cons 2026.
Get Started with Your Cash Out Today
The market doesn’t wait for your bank to finish their audit. Our application process is stripped of all unnecessary red tape. You provide the property info and bank statements; we provide the capital. Every borrower receives a personalized consultation to ensure the loan product matches their specific exit strategy and long-term goals. We are your fast-acting allies in a competitive landscape. Ready to move? Contact Applewood Funding for your Arizona Cash Out Hard Money Loan and unlock your property equity today.
Take Control of Your Arizona Equity Today
Your property equity shouldn’t be a locked asset. It’s your fuel for growth. Whether you’re scaling a rental portfolio in Mesa or handling an emergency at your primary residence in Scottsdale, speed is your most valuable currency. A cash out hard money loan bypasses the months of waiting required by traditional banks. You get the capital you need in days, not months. You’ve built the value; now it’s time to use it.
Applewood Funding specializes in these high-speed, equity-based approvals. As local Arizona experts, we understand the Phoenix and Tucson markets better than any out-of-state corporate lender. Joel McDaniel and our team provide A+ service focused on results, not red tape. We are one of the few lenders offering owner-occupied hard money solutions to ensure every borrower has a path to liquidity. We prioritize your exit strategy and your asset’s potential over your past credit history.
Don’t let opportunity pass you by while a bank reviews your tax returns. Put your equity to work right now. Get Your Fast Cash Out Quote from Applewood Funding and start your next project with confidence. Your financial win is just a few days away.
Frequently Asked Questions
Can I get a cash out hard money loan on my primary residence in Arizona?
Yes. While most private lenders avoid primary residences due to federal regulations, Applewood Funding specializes in owner-occupied hard money loans. This allows homeowners in Phoenix or Scottsdale to access their equity for urgent financial needs when traditional banks decline their applications. We have mastered the compliance hurdles to ensure you get the liquidity you need without the standard institutional delays.
How fast can I receive funds from a hard money cash out refinance?
You can typically close and receive funds in 7 to 14 days. Traditional bank refinances often drag on for 45 to 60 days. Because we prioritize property equity over a borrower’s complex tax history, we can provide a preliminary quote within 24 to 48 hours. This rapid execution is a massive advantage for investors in fast-moving markets like Sedona or Tempe who need capital immediately.
What is the maximum LTV for a cash out hard money loan?
Most equity extractions in Arizona are capped at 65% to 70% Loan-to-Value (LTV). For standard residential investment assets in cities like Mesa or Glendale, we look for a protective equity cushion to secure the transaction. If you’re seeking a cash out hard money loan on vacant land or unimproved property, the LTV limits are generally lower, often settling around 50% based on the current appraised value.
Do I need good credit to qualify for an equity-based cash out loan?
No. Your property’s equity is the primary driver of the approval process. While we review your overall financial picture, a low credit score or a recent bankruptcy won’t automatically disqualify you. We are asset-based lenders. We care more about the value of your Arizona real estate and your specific exit strategy than the number on your credit report. If the equity is there, we can usually find a solution.
What are the typical interest rates for hard money cash out loans in 2026?
In 2026, first-position hard money rates generally range between 8.50% and 13.00%. These rates reflect the speed, flexibility, and lack of red tape associated with private capital. Second-position equity extractions or mezzanine loans may carry higher rates due to the increased risk. We provide transparent terms upfront so you can accurately calculate the return on investment for your specific business or renovation project.
Can I use a bank statement loan for a cash out refinance if I am self-employed?
Yes. We offer specialized bank statement loans for self-employed borrowers across Arizona, from Flagstaff to Tucson. Instead of requiring years of tax returns that might not reflect your true income, we use 12 to 24 months of bank statements to verify your cash flow. This allows business owners with significant trapped equity to access capital based on their actual bankable revenue rather than their taxable income.
What property types qualify for hard money cash out in Arizona?
We fund a diverse range of assets, including single-family rentals, multi-family units, and commercial buildings. We also provide capital for construction projects and vacant land. Unlike institutional lenders, we’re willing to look at properties with unique challenges, such as hauled water systems or shared wells in rural Pinal or Yavapai counties. If the property has value and a clear exit strategy, it likely qualifies for our program.
Is there a prepayment penalty on hard money cash out loans?
Many short-term bridge loans include a minimum interest period or a small prepayment penalty, but we tailor terms to your specific needs. Since these loans usually last 12 to 36 months, we focus on ensuring the timeline matches your exit strategy. Whether you plan to sell the asset or refinance into a long-term mortgage, we discuss all payoff terms during your initial consultation so there aren’t any surprises at closing.