How to Leverage Home Equity with Hard Money: The 2026 Arizona Guide
September 20, 2026
Private Money Cash Out Refinance: Tap Property Equity Fast in 2026
September 22, 2026Equity Cash Out Private Lender: Unlock Your Property Value Fast in 2026
Your property equity is idle capital, not a favor you have to beg a bank to unlock. Yet if you’re self-employed, managing credit hurdles, or chasing an urgent investment opportunity, traditional lenders often drag you through two months of paperwork just to hand you a rejection. Partnering with an equity cash out private lender changes the equation completely. Instead of obsessing over tax write-offs and rigid ratios, private lenders treat your real estate as the primary qualification.
You shouldn’t have to watch profitable opportunities vanish while bank loan committees drag their feet. You deserve direct access to the wealth you’ve already built. In this guide, you’ll discover how to bypass institutional red tape and secure liquid capital in days rather than months. We’ll break down qualification standards, speed-focused application steps, and the exact asset-based strategies you need to pull cash out fast in 2026.
Key Takeaways
- Discover why traditional banks trap your capital behind rigid debt-to-income ratios and why even a 700+ credit score can still trigger a denial.
- Learn how partnering with an equity cash out private lender puts your property value first, cutting funding timelines down from months to days.
- Compare private hard money against conventional bank HELOCs to identify the fastest, most effective way to protect your low mortgage rates while securing liquid cash.
- Find out how self-employed entrepreneurs bypass tax return scrutiny by using straightforward bank statement programs to verify real cash flow.
- Review the exact equity requirements for Arizona properties across Phoenix, Mesa, and Glendale so you can move forward with total confidence.
The Equity Trap: Why Traditional Banks Deny Cash-Out Applications
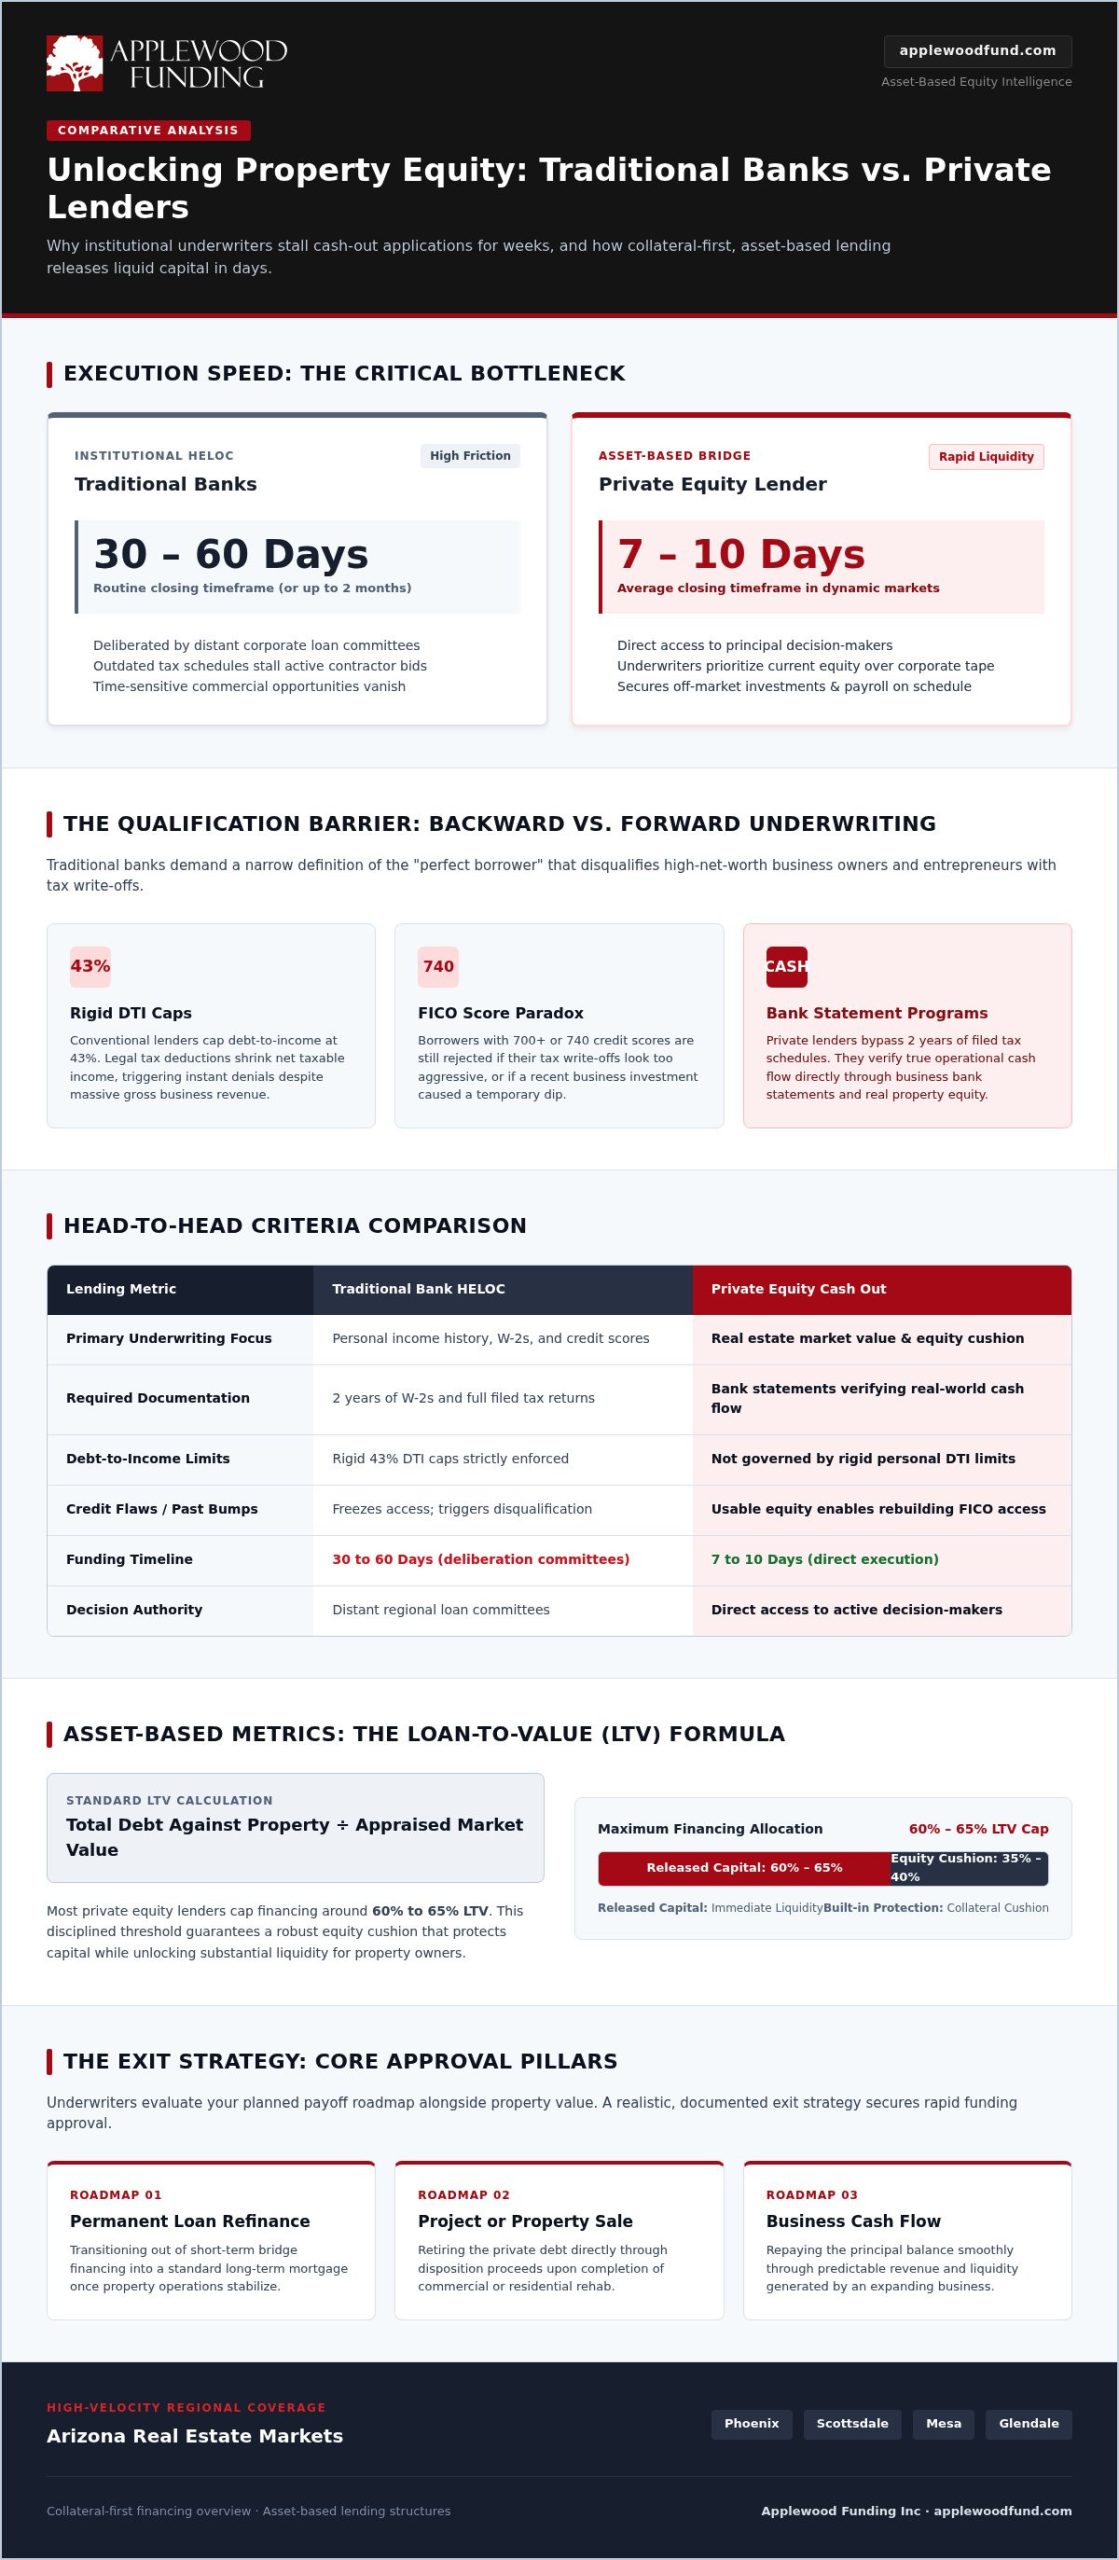
You can hold hundreds of thousands of dollars in property appreciation and still walk out of a commercial bank empty-handed. Institutional lenders rely on a narrow definition of the “perfect borrower.” They want pristine W-2s, low personal debt, and spotless credit reports. If you hold a 740 credit score but run an active business with typical tax deductions, retail underwriters often slam the door shut. They evaluate your financial life through backward-looking paperwork rather than the hard value sitting right inside your real estate.
That gap creates a costly bottleneck. Institutional cash-out applications routinely drag out over 30 to 60 days. While bank loan committees deliberate over outdated tax schedules, time-sensitive property deals disappear and contractor bids expire. Working with a specialized equity cash out private lender breaks this cycle because private underwriters prioritize current equity over corporate red tape.
The Self-Employed Struggle
Aggressive tax write-offs keep your business efficient, but conventional mortgage underwriters view those legal deductions as a lack of income. This creates a painful contradiction: you have strong gross revenue and substantial net worth, yet your net taxable income looks too thin to satisfy rigid 43% debt-to-income caps. A private equity lender removes this friction by assessing real-world cash flow through bank statements instead of demanding two years of filed tax forms.
Credit Score Roadblocks
A recent credit dip from a medical bill, disputed account, or business investment should not freeze your accumulated wealth. Traditional institutions punish past credit hiccups regardless of your current collateral. Private capital operates on an entirely different foundation:
- Underwriting focus: Banks underwrite your personal financial history; private firms issue asset-based hard money loans secured directly by the real estate itself.
- Loan qualification: Usable equity serves as the primary qualification benchmark, allowing borrowers with rebuilding FICO scores to access substantial liquidity.
- Speed of execution: Because asset value takes center stage, an equity cash out private lender can evaluate the collateral and deliver funding decisions without weeks of bureaucratic delays.
What is an Equity Cash Out Private Lender?
An equity cash out private lender is a specialized non-bank financing partner that provides loans secured directly by the market value of your real estate. While institutional banks fixate on two years of W-2 tax forms and rigid debt ratios, private lenders operate on a straightforward reality: your property is the collateral, not your personal employment history. Speed is the true currency here. When you need immediate capital for an expanding business, commercial property rehab, or short-term bridge financing, waiting months on bank underwriting isn’t an option.
Asset-Based Lending Explained
Asset-based lending evaluates loan eligibility primarily by the property’s equity cushion through the loan-to-value ratio rather than the borrower’s personal tax history.
To calculate loan-to-value (LTV), a lender divides the total debt against the property’s appraised market value. Most private equity lenders cap financing around 60% to 65% LTV, ensuring built-in downside protection while releasing substantial cash to the borrower. Underwriters also evaluate your planned exit strategy. Whether you intend to refinance with a permanent loan, sell a completed project, or repay the balance through business cash flow, having a realistic payoff roadmap is the key to securing rapid approval.
The Private Lender Advantage
Working with private capital gives you direct access to the actual decision-makers. You don’t have to wait on distant corporate loan committees to review voluminous paperwork. According to the Consumer Financial Protection Bureau’s guide to HELOCs, traditional revolving equity products depend heavily on personal income ratios and credit scores, which routinely drags out closings for 30 to 60 days. Private lending cuts through that delay with flexible structures designed for fast turnaround.
In high-demand markets across Scottsdale and Phoenix, real estate moves quickly. Private funding closes in 7 to 10 days, letting you secure off-market investments or fund business payroll before competitors even get conditional bank approvals. If you need to access your hard-earned equity without institutional friction, you can speak directly with an Arizona private financing specialist to evaluate your options.
Private Hard Money vs. Conventional HELOCs: 2026 Comparison
Conventional Home Equity Lines of Credit (HELOCs) often sound appealing because of lower headline rates. But cheap credit does you no good if it arrives two months too late. Banks take 60 days or more to process HELOC applications, burying borrowers under tax audits and exhaustive income verification. Worse, financial institutions retain the contractual right to freeze or reduce open credit lines whenever broader market conditions soften. Partnering with an equity cash out private lender bypasses that institutional control by providing a fast, reliable lump-sum payout secured by your hard collateral.
The core difference comes down to qualification philosophy. Traditional lenders treat equity as a secondary backup to personal income. They scrutinize tight debt ratios and demand spotless tax filings. Reviewing official FTC guidance on borrowing against home equity reveals how conventional equity products tie directly to consumer debt profiles and backward-looking income checks. In contrast, an equity cash out private lender looks at the equity spread in the real estate itself, approving transactions with zero restrictions on how you deploy your capital.
When Hard Money Beats a HELOC
Speed creates leverage. If you uncover an undervalued property flip, waiting eight weeks for a retail bank appraisal means watching a competing cash buyer walk away with the profit. Missing a substantial discount just to save two points on interest makes no financial sense. Fast bridge financing also rescues businesses facing immediate cash flow pinches or maturing obligations. When conventional lenders decline a refinance request, a private money cash out refinance delivers immediate liquidity to stabilize operations and capture revenue.
Understanding the Trade-offs
Private capital serves a distinct purpose. It isn’t built to replace a thirty-year conventional mortgage. Instead, hard money functions as a rapid, short-term bridge designed to solve immediate capital hurdles over 12 to 36 months. You pay a higher rate for speed, flexibility, and absolute certainty of execution. When evaluating hard money loan pros and cons, experienced investors treat the rate premium as an ordinary operational expense that unlocks far greater returns.
Qualifying for a Private Equity Loan in Arizona
Property values across Phoenix, Mesa, and Glendale have expanded dramatically over recent years, giving local real estate owners substantial borrowing power. Qualifying with an equity cash out private lender doesn’t require jumping through typical bank hoops. You can leave stacks of personal tax returns and IRS transcripts behind. Approval rests almost entirely on usable equity, property valuation, and clean title history.
Arizona lending statutes under A.R.S. § 44-1201 exempt written business and commercial real estate contracts from usury caps. This straightforward legal structure allows local private lenders to draft custom loan agreements quickly. As long as your title is free of unresolved tax liens and the asset retains adequate value, getting approved is fast and direct.
Property Types That Qualify
Private capital finances a diverse range of real estate assets across Arizona:
- Residential rentals and multi-family units: Single-family investment properties, duplexes, and multi-unit apartment complexes.
- Primary residences: While most non-bank lenders strictly avoid personal residences, specialized programs for owner-occupied hard money loans allow homeowners to access their equity compliantly up to 65% LTV.
- Commercial parcels and land: Infill parcels, retail buildings, light industrial warehouses, and entitled construction land waiting for development.
The 3-Step Arizona Approval Process
Accessing your capital shouldn’t take all quarter. Working with a dedicated equity cash out private lender boils the closing cycle down into three clear milestones:
- Step 1: The Initial Equity Review. Submit your property address, existing lien payoff balance, and requested loan amount. You get direct feedback within 24 to 48 hours without submitting tax forms.
- Step 2: Rapid Valuation and Title Search. Local underwriters assess neighborhood comparables, inspect property condition, and order a preliminary title report to verify ownership.
- Step 3: Documents and Valley Funding. Loan documents are drawn and delivered to a local Arizona title agency. Once signed, funds transfer to your escrow account in as little as 7 to 10 days.
Ready to put your real estate equity to work on your next deal? Apply for an Arizona cash-out loan today to review your usable equity with our local lending team.
Applewood Funding: Your Arizona Partner for Rapid Equity
Institutional lenders continue to reject viable applicants who fall outside rigid corporate molds. Applewood Funding operates with a different mindset. Serving the state continuously since 1996 under principal broker Joel McDaniel (NMLS #175371, AZ MB #0903207), our team works as an agile financial ally for local property owners. We focus on real-world equity rather than bureaucratic checkboxes, providing loan amounts from $20,000 to over $5,000,000 with initial terms delivered in 24 to 48 hours.
For independent entrepreneurs, standard W-2 requirements create an unfair hurdle. Applewood solves this barrier with specialized bank statement loans for self-employed borrowers, qualifying your liquidity through 12 to 24 months of actual bank deposits. Even better, while almost all private lenders refuse owner-occupied primary residences due to federal compliance overhead, Applewood delivers fully compliant owner-occupied hard money loans up to 65% LTV across Arizona. As an experienced equity cash out private lender, we structure fast capital that keeps your projects moving.
Tailored Solutions for Local Borrowers
Arizona real estate is nuanced. A luxury property in Scottsdale functions under entirely different economic drivers than a hospitality parcel in Sedona or high-altitude acreage in Flagstaff. National out-of-state lenders rarely understand these regional distinctions, causing appraisals to stall and deals to collapse. Joel McDaniel and the Applewood team provide deep local underwriting expertise, cutting through institutional delays to fund transactions directly through trusted Arizona title agencies.
Next Steps to Liquidity
Extracting the cash locked in your portfolio shouldn’t require months of uncertainty. To get started, gather basic asset details including your current property address, estimated market value, and an outline of your existing lien balances. Review our guide on how a private money cash out refinance can accelerate your equity access to plan your optimal financing structure. When you need immediate capital to capture a time-sensitive investment, secure a customized cash out hard money loan with Applewood Funding and take complete control of your real estate wealth today.
Unlock Your Real Estate Equity on Your Terms
Don’t let bank bureaucracy lock up the wealth you’ve worked hard to build. Waiting two months for institutional approvals costs you time, momentum, and profitable investment deals. Partnering with an experienced equity cash out private lender puts your real estate value to work immediately, bypassing personal tax hurdles and rigid underwriting formulas.
Whether you need to bridge a commercial acquisition or tap equity through a dedicated owner-occupied hard money specialist, you need a partner who knows the local territory. Applewood Funding brings decades of direct Arizona local expertise to your corner, cutting red tape to deliver funding in as little as 7 days. Take the decisive step toward your financial goals. Get your Arizona equity cash-out quote in 24 hours and put your capital back where it belongs.
Frequently Asked Questions
Is it possible to get a hard money cash-out loan on my primary residence?
Yes, you can secure hard money financing on your primary residence in Arizona through specialized private lenders. While most firms avoid owner-occupied properties due to strict federal consumer lending rules, Applewood Funding provides compliant financing for primary homes. Borrowers across Phoenix, Scottsdale, and Tucson can access cash against their equity without navigating conventional bank delays.
How much equity do I need to qualify for a private lender cash-out?
Most private capital programs require you to retain at least 35% to 40% equity in the property after closing. Working with an equity cash out private lender typically means working within a maximum 60% to 65% loan-to-value cap. This built-in equity cushion protects both parties and eliminates the need for mortgage insurance or intrusive personal financial audits.
Can I get an equity loan if I am self-employed with no tax returns?
Yes, self-employed borrowers can qualify without handing over tax returns by using specialized bank statement loan programs. Instead of evaluating net income after business write-offs, private underwriters verify your financial strength through 12 to 24 months of verified bank account deposits. This allows active business owners throughout Mesa and Glendale to qualify based on real operational cash flow.
How fast can a private lender fund an equity cash-out in Arizona?
Private equity funding can close in as little as 7 to 10 days once your property details and preliminary title work are clear. Because underwriting decisions are handled locally rather than through out-of-state corporate committees, you receive initial loan terms within 24 to 48 hours. This rapid execution gives Arizona investors immediate liquidity to capture time-sensitive market opportunities.
What are the typical interest rates for hard money cash-out loans in 2026?
Hard money cash-out loans carry higher interest rates than conventional 30-year mortgages because private capital prioritizes speed, flexible underwriting, and short-term convenience. Rates reflect the bridge nature of the financing, designed to solve immediate liquidity needs over 12 to 36 months before you refinance or sell. Exact pricing depends on your property type, location, and overall leverage.
Do I need a high credit score to work with a private equity lender?
No, you do not need pristine credit to qualify with an equity cash out private lender. Asset-based lenders focus on your property’s current market value and your planned exit strategy rather than past financial blemishes. Borrowers recovering from recent credit events or managing irregular income can still access substantial capital if sufficient collateral equity exists.
What happens if I cannot pay back the hard money loan on time?
If your exit strategy hits delays, communicate with your lender before maturity to discuss extending your term. Under Arizona law (A.R.S. § 33-808), non-judicial foreclosure through a deed of trust requires a mandatory 90-day Notice of Trustee’s Sale. Responsible private lenders prefer working out modified payoff structures rather than initiating formal property recovery actions.
Can I use a private equity loan for business expenses?
Yes, you can deploy funds from a private equity cash-out for almost any legitimate commercial or business purpose. Real estate investors and business owners across Peoria, Tempe, and Flagstaff regularly utilize this capital to purchase inventory, cover unexpected payroll, fund urgent facility repairs, or bridge gaps between larger project receivables without institutional oversight.