Land Development Financing: A Step-by-Step Guide for 2026
September 26, 2026Tucson Bank Statement Mortgage Lenders: How to Compare Your Options in 2026
The lender with the lowest advertised rate may not be the one that understands your business income best. If tax write-offs make your returns look smaller than your current cash flow, comparing tucson bank statement mortgage lenders means looking beyond a headline rate.
It’s reasonable to want clear answers before sharing financial documents. Bank statement loans let lenders assess income using personal or business statements, but requirements and calculations vary. The right fit depends on how a lender reviews your deposits, which documents it needs, and whether its terms work for your plans.
This guide explains what lenders may review beyond tax returns and gives you consistent questions to ask about rates, fees, statement history, and written loan terms. You’ll also find a practical checklist to help you prepare for an initial review. Applewood Funding Inc offers bank statement loans for self-employed borrowers. Confirm directly whether your Tucson property is eligible, along with current requirements and terms. Start with program fit, income analysis, and written details rather than marketing claims.
Key Takeaways
- A bank statement mortgage may help self-employed borrowers document deposits when tax returns don’t tell the full story.
- Ask each of the tucson bank statement mortgage lenders you consider how it calculates income and which documents its program accepts.
- Compare written terms side by side, including fees, estimated timelines, and how the lender will communicate with you.
- Before sharing sensitive records, confirm Tucson property eligibility and use a secure channel to submit documents.
- Prepare a brief overview of your finances and property plans so lenders can explain program fit and next steps.
What Tucson borrowers should know about bank statement mortgage lenders
A bank statement mortgage is a home loan that may use deposits shown in financial statements to assess a self-employed borrower’s income, rather than relying solely on tax-return income. It’s still a mortgage loan secured by property, but the income review may differ from conventional underwriting. Documents, calculations, and eligibility rules depend on the lender and program. There is no single standard that every lender follows.
That distinction matters because business revenue is not the same as qualifying personal income. A business may have substantial deposits alongside expenses, transfers, or other transactions that a lender treats differently. Ask how the program separates revenue from income and what adjustments it applies. Don’t assume every deposit will count dollar for dollar or that different lenders will calculate income the same way.
How bank statement mortgages may fit self-employed borrowers
Tax deductions can reduce reported taxable income, even when a business has active cash flow. A bank statement program may give a lender another way to review a borrower’s finances, but the lender still needs to determine which income qualifies under its criteria.
Before applying, ask which statements the program accepts, how it calculates income, and what additional documentation may be required. Bank statement financing isn’t automatically the right fit. The outcome depends on the lender’s review, your full financial picture, and the program’s terms.
Why confirm Tucson and Pima County availability first
Start with the property location and loan purpose. Tell each lender where the property is, whether you plan to occupy it, and what type of property you’re considering. Then ask directly whether the specific program is available for properties in Tucson and elsewhere in Pima County, and whether your occupancy plans meet its requirements.
An Arizona-based lender doesn’t necessarily offer every program for every Tucson property. Service area and program eligibility are separate questions. Confirm both before sending a full application or sensitive records.
Applewood Funding offers bank statement loans for self-employed borrowers. If you’re considering the company, ask it to confirm current Tucson and Pima County availability, property eligibility, documentation requirements, and terms. Use the same questions with other tucson bank statement mortgage lenders so you can compare their answers on equal footing instead of relying on broad marketing language.
What Tucson bank statement mortgage lenders may review
Expect a lender to ask how your business earns income and which records support it. Document requirements aren’t universal and may vary by lender and program. Some lenders may request personal bank statements, business bank statements, or both. Before sending documents, ask which account types and statement periods the specific program accepts for an initial review.
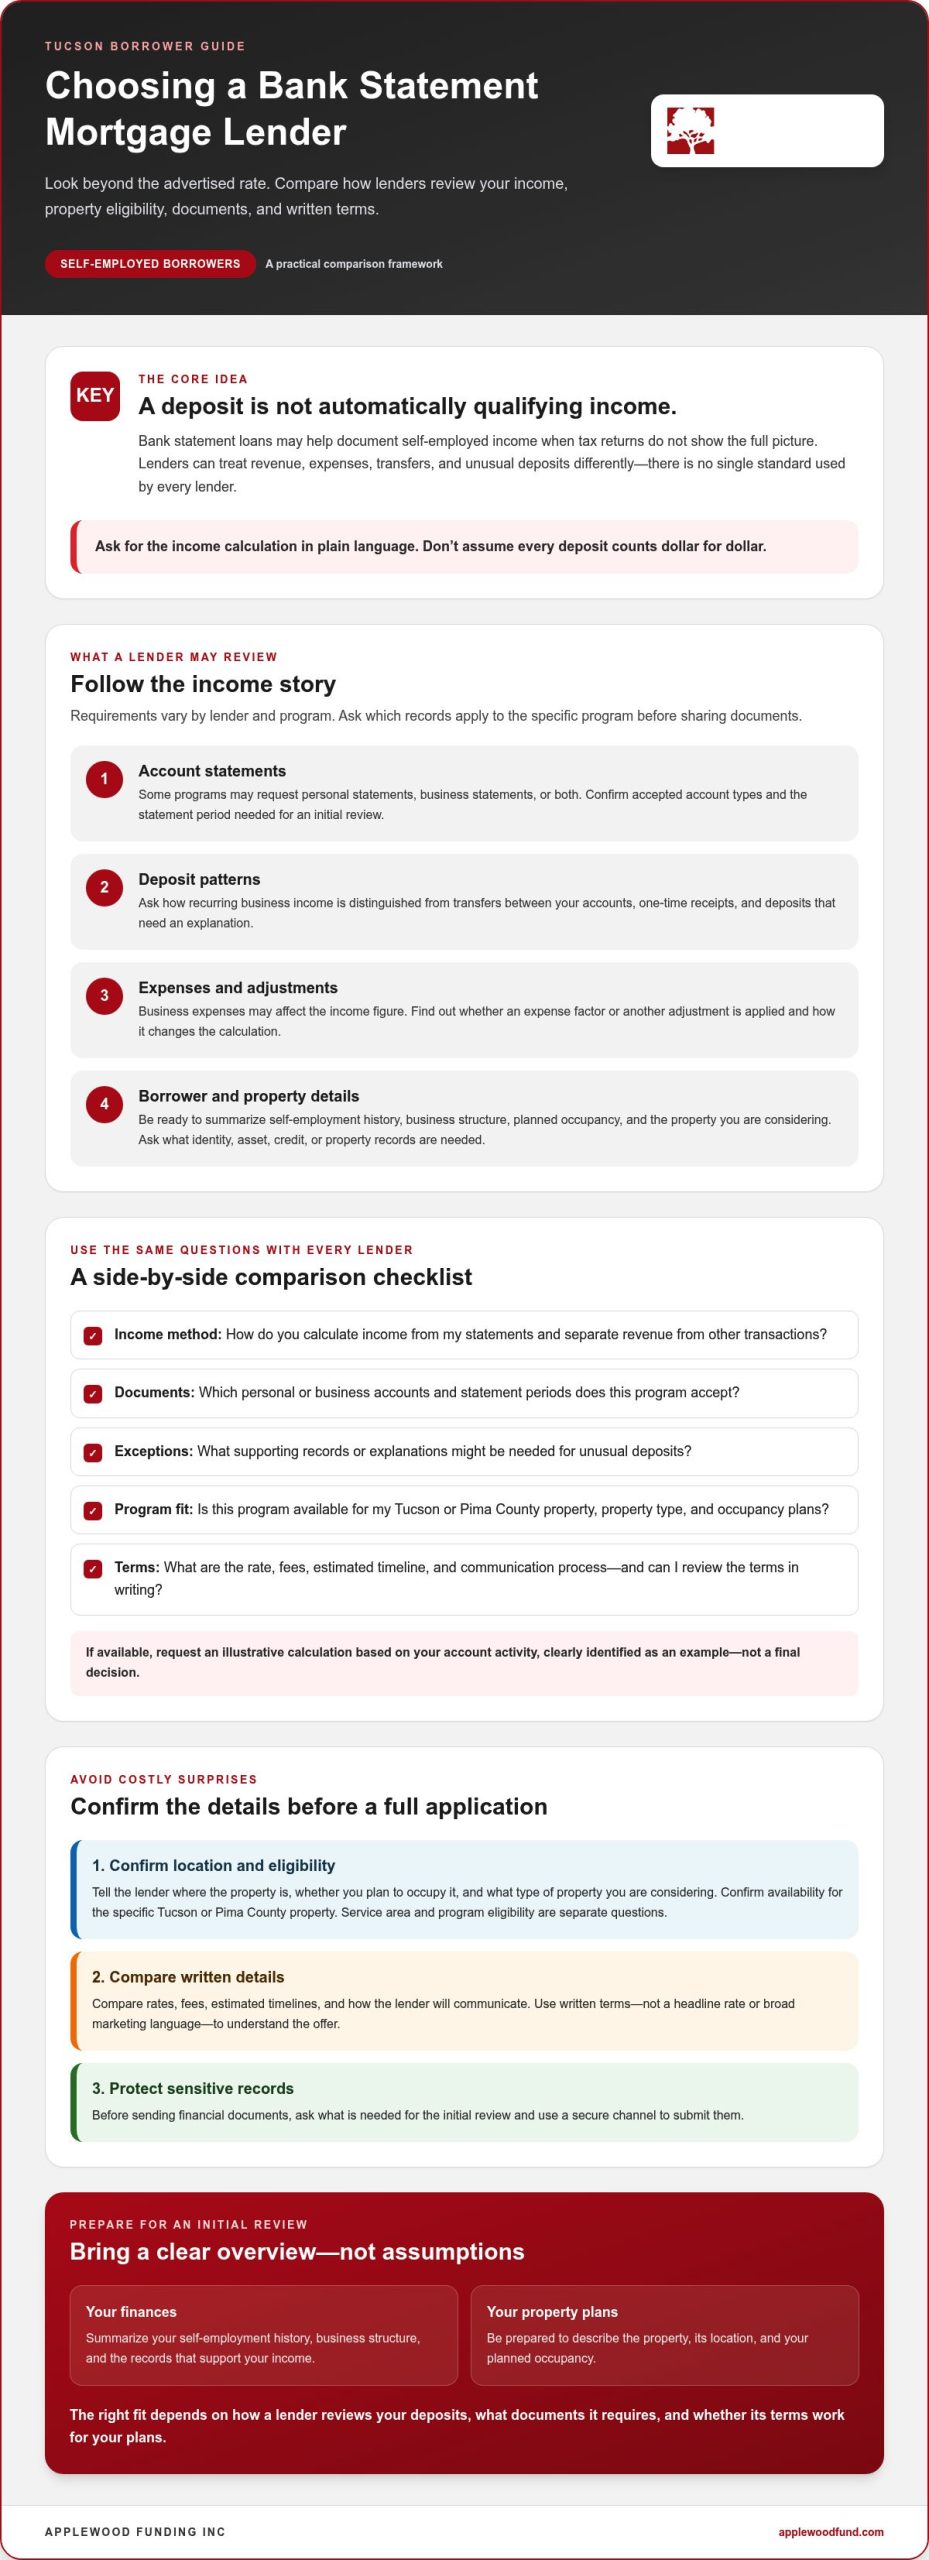
Deposits shown on a bank statement are not automatically qualifying income. A lender may treat recurring revenue differently from transfers between your own accounts, one-time receipts, or funds that need an explanation. Business expenses may also affect the income figure used in its review. Ask for the calculation method in plain language, not just a summary number.
Questions to ask about statements and income calculations
Use the same questions with each lender so you can compare the answers:
- Which personal or business accounts can I use, and what statement period does this program require?
- How do you identify recurring income and distinguish it from transfers, unusual deposits, or one-time receipts?
- Do you apply an expense factor or another adjustment to business deposits? How does that change the income figure you use?
- What explanations or supporting records might you request for deposits that aren’t part of my normal business activity?
If the lender can do so without presenting the result as a final decision, ask for an example based on your account activity. This can help you understand whether its method fits your business before you move further into the process.
Other borrower and property details to have ready
Along with account records, prepare a concise summary of your self-employment history, business structure, planned occupancy, and the property you’re considering. Don’t guess which documents the lender needs. Ask whether the initial review calls for identity, asset, credit, or property documents, and how to submit them securely.
Don’t rely on a credit-score, income, or reserve threshold quoted for a different program. Ask the lender to confirm its current criteria for your situation and explain what could affect the review. Keep the answers in writing where possible.
Applewood Funding offers bank statement loans for self-employed borrowers. Confirm Tucson availability and current program requirements directly. If you’re contacting the company, start with its bank statement loan information and ask which records it needs, how it calculates eligible income, and which secure submission method to use.
How to compare Tucson bank statement mortgage lenders
Compare the process and the written offer, not just the headline rate. Give each lender the same borrower and property details, then record what each one confirms. A side-by-side comparison makes differences easier to spot and helps you ask follow-up questions before deciding whether to proceed.
| What to compare | Questions to ask |
|---|---|
| Program fit | Does this program fit my property location, occupancy plans, and borrower profile? |
| Accepted documents | Which account types and statement periods are accepted? What else may be requested? |
| Income method | How are deposits, business expenses, transfers, and unusual receipts treated? |
| Fees and terms | What rate, fees, points, term, payment structure, and prepayment conditions apply? |
| Timeline | What steps remain, and what could affect the estimated timing? |
| Communication | Who reviews the file, answers questions, and shares key decisions? |
Compare the complete written loan offer
Ask each lender to put the proposed rate, fees, points, loan term, payment structure, and any prepayment conditions in writing. Confirm which figures are estimates and which depend on underwriting or property review. Compare like with like by using the same loan amount, occupancy plan, property assumptions, and expected timing for every quote. If a term is unclear, ask for a plain-language explanation before treating the offers as comparable.
Evaluate lender communication and process clarity
A clear process matters. Can the lender explain why it needs a document and how it calculates eligible income? Ask who will review your file, who you can contact with questions, and when you’ll hear about important decisions. Confirm how sensitive financial records are submitted, stored, and accessed. Don’t send them through an unverified channel.
Online reviews can provide context about other borrowers’ experiences, but they can’t predict your result. Programs, files, and property details differ. Assess each lender based on its answers and written terms for your situation.
For more background before weighing proposals, read Applewood Funding’s bank statement loan guide. Then use the same comparison framework with the tucson bank statement mortgage lenders you contact. Consistent questions and written answers make it easier to reach a clear decision.
How to avoid costly surprises before choosing a Tucson lender
Take the time to verify the details before you commit or share sensitive records. This sequence can help you identify gaps early:
- Verify service area: Confirm the lender considers properties in Tucson and Pima County, and ask whether your occupancy plans fit.
- Request program details: Get the document requirements, income calculation method, and conditions that apply to your situation.
- Compare written terms: Review the complete offer alongside other proposals using the same borrower and property assumptions.
- Decide whether to proceed: Move forward only when you understand the costs, conditions, and next steps.
Watch for vague fees, promises that aren’t documented, and income calculations the lender can’t explain clearly. Be cautious if you’re pressured to submit sensitive documents before your questions are answered. Ask what could change after underwriting or property review, and request clarification in writing. Approval, timing, and final terms depend on the individual file and property, so don’t treat an estimate as a guarantee.
Questions that reveal program fit and potential trade-offs
Ask why the lender thinks bank statement financing may suit your documented income and goals, and whether another mortgage route might also be worth exploring. Have the lender explain costs, conditions, payment features, and any terms that could change before closing. If an answer is unclear, pause and ask for an explanation before sharing sensitive records or accepting an offer.
When to compare another mortgage route
Bank statement financing isn’t the only possible path. Ask whether a conventional or other mortgage program could fit your documented income and plans. Compare eligibility and the full written terms, not just one headline rate. Review the program details before weighing your options.
Use this process with every lender you consider. A useful comparison relies on the same assumptions, clear answers, and written terms. If you want to ask Applewood Funding about its bank statement loans for self-employed borrowers, contact the team to confirm Tucson availability and current program details. Confirm the company’s Tucson service area, property eligibility, and terms directly.
Next steps for finding a bank statement mortgage lender in Tucson
Start with a short overview, not a complete set of sensitive records. Before contacting tucson bank statement mortgage lenders, prepare a clear summary of your self-employment, the property you’re considering, and what you want the loan to accomplish. This gives a lender enough context to explain its initial review process and identify questions to resolve.
Prepare for an initial lender conversation
Write down the basics: how long you’ve been self-employed, your business structure, whether the property will be owner-occupied, and whether you’re planning a purchase or refinance. Include the property’s location and your expected timing. You don’t need to send complete financial records just to start a conversation.
Ask what information is needed for a preliminary review, which documents may be requested later, and how the lender securely receives financial records. Keep a written log of each lender’s requirements, answers, follow-up questions, and any conditions it mentions. This makes it easier to compare details without relying on memory.
Ask Applewood Funding about your Tucson financing options
Confirm current Tucson and Pima County availability, property eligibility, and program requirements directly. Ask whether the lender can consider your specific property and occupancy plan, which documents it would need, how it reviews income, and which terms it can provide in writing.
Use the first conversation to understand program fit, not to assume approval. Ask about next steps and clarify any geographic restrictions before sending sensitive records. If you’re considering another route, ask which options the lender can discuss for your goals. Compare the answers and written terms before deciding how to proceed.
Ready to start that conversation? Contact Applewood Funding to discuss your mortgage options. Reaching out is a way to ask about current program fit and terms, not a guarantee of eligibility or approval.
Take Your Next Mortgage Step With Clear Answers
A bank statement loan may give self-employed borrowers another way to document income when tax returns don’t show the full picture. Lender programs differ, so compare how each one reviews deposits and calculates qualifying income. Then weigh written terms, costs, and conditions side by side.
As you compare tucson bank statement mortgage lenders, confirm that a lender can consider your Tucson property and ask which documents and program terms apply to your situation. Contact the team directly to verify Tucson availability, current program fit, and written terms before deciding whether to proceed.
Contact Applewood Funding to discuss your Tucson mortgage options. Bring your questions, request clear answers, and take the next step with confidence.
Frequently Asked Questions
Can self-employed borrowers get a mortgage using bank statements in Tucson?
Yes, some lenders offer bank statement loans for self-employed borrowers, but eligibility depends on the lender’s current program and its review of your finances and property. These loans may let a lender assess documented deposits rather than relying only on tax-return income. If you’re comparing tucson bank statement mortgage lenders, confirm that a lender can consider your Tucson property and occupancy plans before submitting a full application.
How many months of bank statements do mortgage lenders require?
Requirements vary by lender and program. Some bank statement mortgage programs may ask for 12 or 24 months of personal or business statements, but those periods don’t apply to every lender or borrower. Ask which account types and statement dates the specific program accepts, and whether you’ll need additional records to explain deposits or account activity. Confirm the current document list before gathering or sending sensitive files.
Do bank statement mortgage lenders verify business income?
Yes. Lenders review the records they request to determine what income may qualify under their program. For business accounts, they may distinguish recurring customer payments from transfers, one-time receipts, and business expenses. Deposits aren’t automatically treated as qualifying income, and calculation methods differ. Ask the lender to explain any expense factor or other adjustment in plain language, and find out what supporting documents it may need.
Can I get a bank statement mortgage without tax returns?
Possibly, but don’t assume tax returns won’t be requested. A bank statement loan may assess documented deposits without relying solely on tax-return income, yet each lender sets its own documentation requirements. Ask whether returns are needed for an initial review, later underwriting, or another part of the file. Confirm which statements and supporting records the program accepts before sharing complete financial documents.
Are bank statement mortgage rates higher than conventional mortgage rates?
They may be, but there’s no single rate that applies to every borrower or lender. Pricing depends on the program, borrower details, property, and other loan terms. Compare written, personalized offers using the same loan amount, occupancy, property assumptions, and timing. Look beyond the interest rate by reviewing fees, points, payment structure, loan term, and any prepayment conditions.
How do I know if a bank statement lender serves Tucson?
Ask directly whether the lender can consider the specific property address in Tucson or elsewhere in Pima County, and confirm any occupancy or geographic restrictions. An Arizona-based lender may not offer every program in every area. For a property in Tucson, Phoenix, Scottsdale, Glendale, Peoria, Tempe, Mesa, Sedona, or Flagstaff, verify location eligibility and program availability before sending sensitive records.
What should I compare when choosing a bank statement mortgage lender?
Compare program fit, accepted statement types and periods, income calculation method, written fees and terms, estimated timeline, and communication process. Ask who reviews your file, who answers questions, and which figures remain subject to underwriting or property review. Use the same borrower and property assumptions for each offer. Clear explanations and written details make it easier to assess your options without relying on marketing claims or another borrower’s experience.