Bank Statement Loans 2026: The Ultimate Guide for Self-Employed Borrowers
September 14, 2026Self Employed Home Loan No W2: Your 2026 Guide to Alternative Financing
Why should a smart tax deduction cost you your dream home? For most entrepreneurs, a lean tax return is the goal. To a big bank, it looks like you’re broke. If you’ve been told you need a 9-to-5 to qualify for a mortgage, they’re wrong. Securing a self employed home loan no W2 isn’t just possible in 2026; it’s the new standard for the 16.5 million Americans who run their own show. You have the cash flow. You have the equity. It’s time for a lender who understands how business actually works.
We get it. The traditional lenders see your write-offs and hit the “reject” button before you even finish the application. It’s frustrating to have the capital but not the specific paperwork they demand. This guide changes the game. You’ll learn how to use 12 to 24 months of bank statements to prove your real earnings and bypass the W2 hurdle entirely. We’re laying out a clear path to homeownership with speedy approvals and common-sense underwriting tailored for the Arizona market. No more red tape. Just a straight line to your new front door.
Key Takeaways
- Stop letting tax write-offs disqualify you from homeownership by leveraging bank statement loans that prioritize your actual business cash flow.
- Discover the exact steps to secure a self employed home loan no W2 using 12 to 24 months of average monthly bank deposits.
- Learn how owner-occupied hard money serves as a powerful solution when you have significant equity but lack traditional income documentation.
- Audit your business deposits effectively to separate revenue from transfers and eliminate the red tape that stalls big bank approvals.
- Gain a competitive edge in the Arizona market by utilizing common-sense underwriting that values your business success over rigid W2 requirements.
The W2 Barrier: Why Traditional Mortgages Fail the Self-Employed
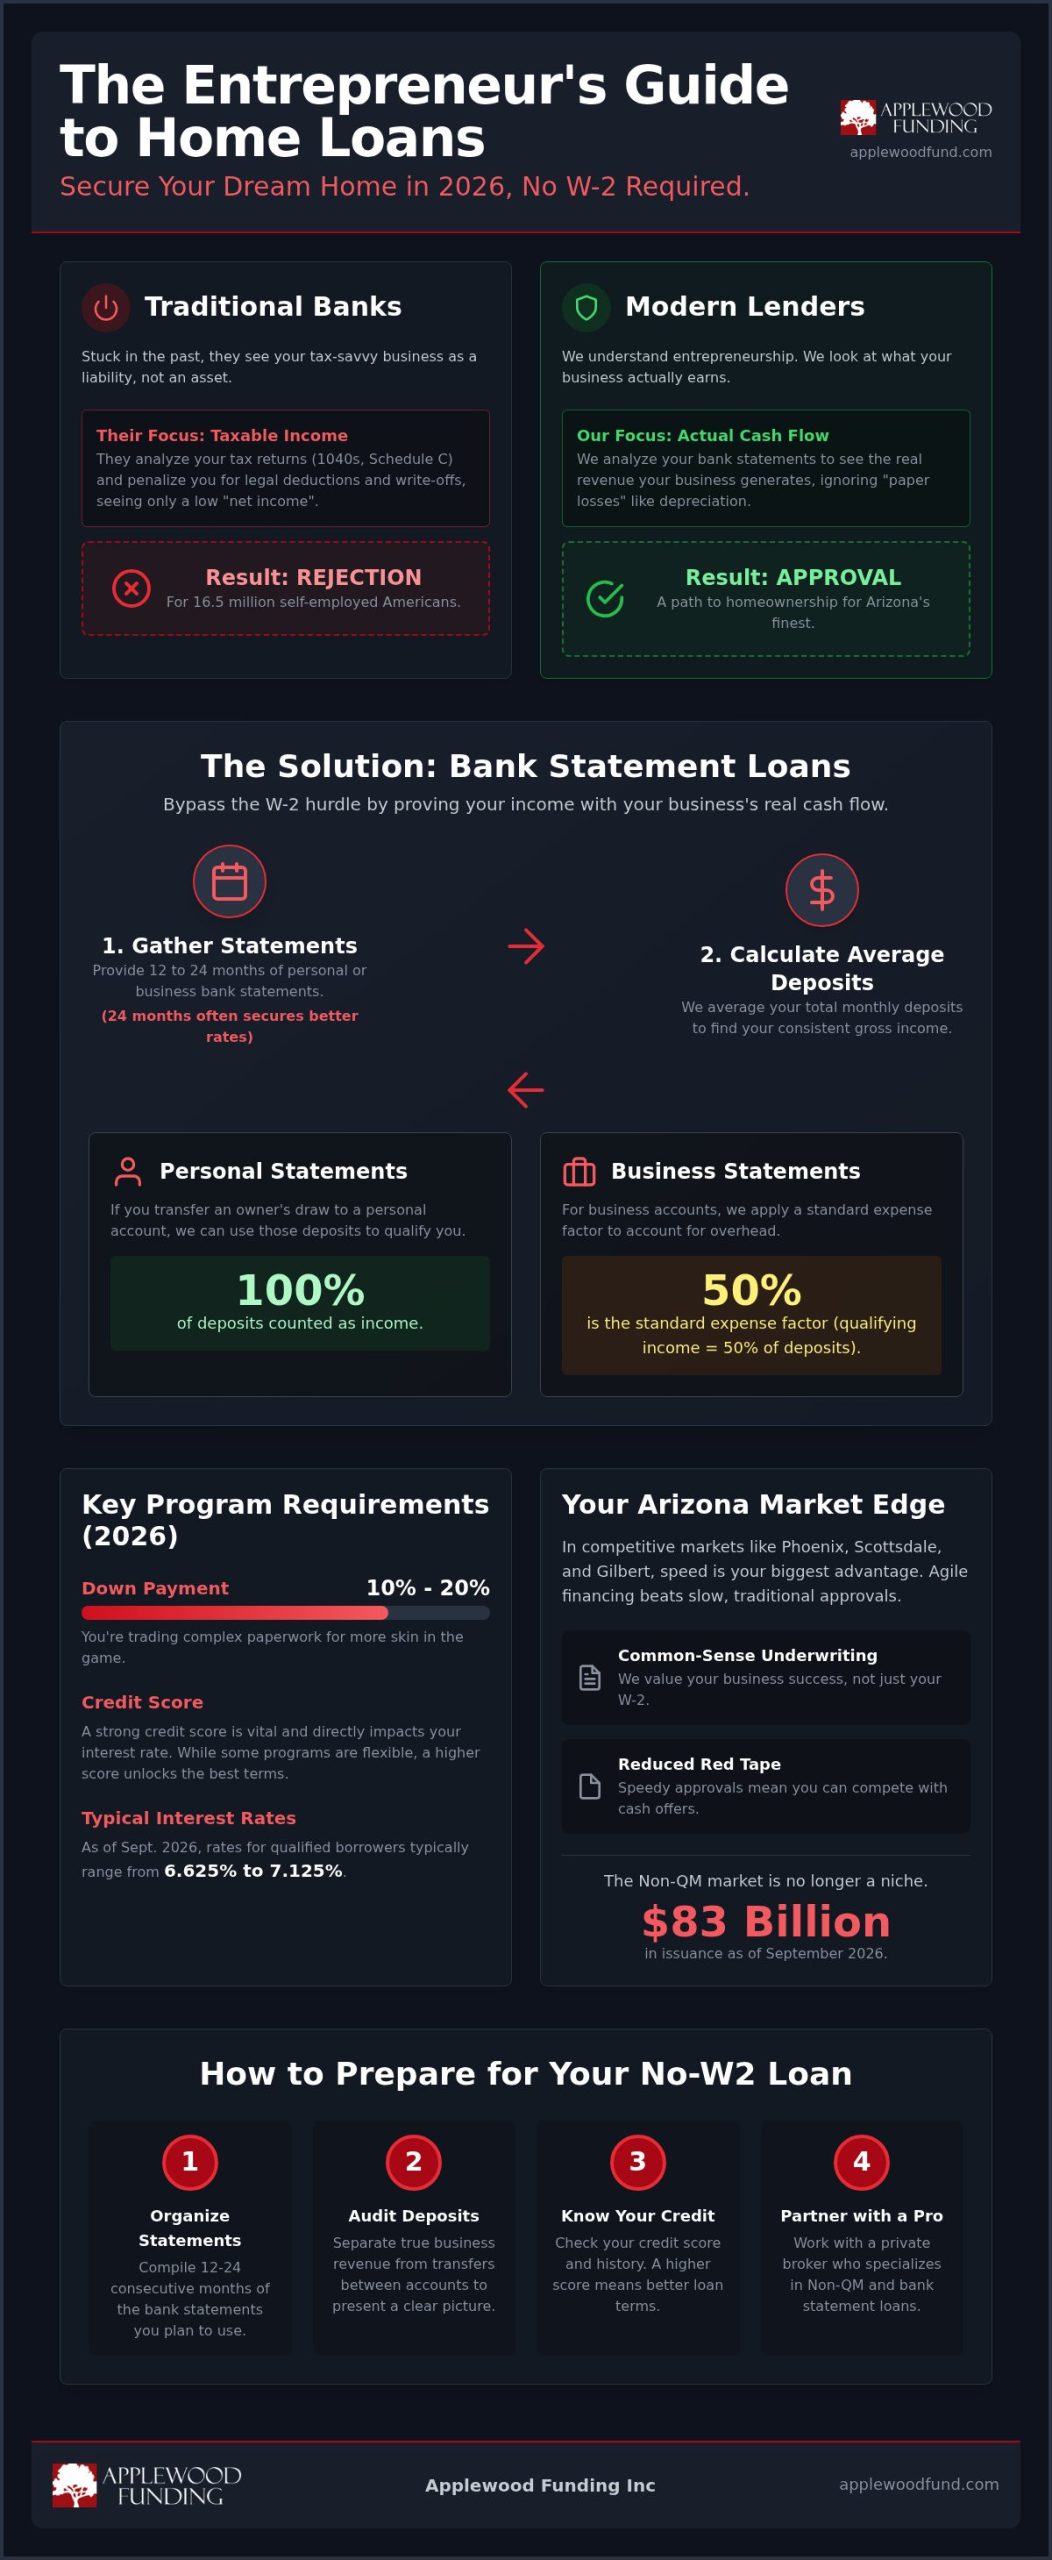
Traditional banks love employees. They love steady, predictable paystubs and the safety of a corporate seal. If you’re a business owner, they see a risk, not a success story. This is the paradox of the modern entrepreneur. Your business might generate $500,000 in revenue, but after your CPA applies every legal deduction, your taxable income looks like a hobbyist’s. When you apply for a self employed home loan no W2, the big banks look at line 31 of your Schedule C and walk away. They aren’t being mean; they’re stuck. Federal “Qualified Mortgage” (QM) rules force them into a rigid box. They can’t look at your bank balance or your business growth. They can only look at your 1040 tax return.
The emotional toll is real. You’ve put in the 80-hour weeks. You’ve built equity. Yet, on paper, you’re “unbankable.” It feels like you’re being punished for being successful and tax-efficient. This frustration is why many are turning back to flexible financing models. While the old No-documentation loan programs of the past had a bad reputation, today’s alternative financing is built on common sense and real cash flow. It’s about proving you can pay the mortgage, not proving how much you paid the IRS.
The Problem with Heavy Tax Deductions
Underwriters at traditional institutions are trained to find reasons to say no. When they see heavy depreciation or significant business expenses, they slash your qualifying income. They don’t “add back” the costs that didn’t actually leave your pocket. This creates a massive Debt-to-Income (DTI) problem. For a self employed home loan no W2, we look past the paper losses. We understand that a deduction for a new fleet of vehicles shouldn’t stop you from buying a house in Scottsdale.
- Gross vs. Net: Big banks care about net profit; we focus on your actual gross deposits.
- Paper Losses: Depreciation is a tax benefit, not a sign of financial weakness.
- Underwriting Bias: Traditional systems aren’t built to handle “lumpy” business income.
Why 2026 is Different for Arizona Borrowers
The Arizona real estate market doesn’t wait for 45-day bank approvals. In cities like Phoenix, Gilbert, and Scottsdale, speed is your only leverage. Traditional closings are losing to agile buyers who can move in days, not months. At Applewood Funding Inc, we see the rise of Non-QM lending as a necessity, not an alternative. As of September 2026, the non-QM market has already reached $83 billion in issuance. It’s no longer a niche. It’s how the modern Arizona workforce gets funded. If the big banks won’t move, we will.
What is a Bank Statement Loan? The No-W2 Solution
Tired of the corporate W2 obsession? A bank statement loan is the ultimate pivot for the modern entrepreneur. It’s a mortgage that calculates your qualifying income by averaging your monthly bank deposits instead of looking at a tax return. It’s simple. It’s effective. This program is specifically designed for 1099 contractors, freelancers, and S-Corp owners who need a self employed home loan no W2 but have the cash flow to prove their worth. You don’t need to explain your deductions to an algorithm. You just need to show your deposits.
Lenders typically review either 12 or 24 months of your banking history. Opting for a 24-month look-back often secures a more competitive interest rate, which in September 2026 typically ranges from 6.625% to 7.125%. The “secret sauce” here is the expense factor. Lenders know running a business has costs. If you use business bank statements, underwriters apply a standard expense ratio, often 50%, to your total deposits. If you deposit $20,000 a month, they qualify you on $10,000. It’s a transparent, common-sense calculation that reflects your real-world buying power.
Personal vs. Business Bank Statements
Where you park your revenue matters. If you transfer your owner’s draw into a personal account, lenders can often count 100% of those deposits toward your income. Business accounts are treated differently. Because of overhead like rent, payroll, and supplies, the 50% expense haircut is the standard. If your business has exceptionally low overhead, a letter from your CPA can sometimes lower that expense factor, giving you even more leverage. Many Arizona borrowers also mix income sources. If you have a side W2 job and a main business, we can blend both to maximize your loan amount.
Credit Score and Down Payment Requirements
You’re trading a mountain of paperwork for a bit more skin in the game. In 2026, most bank statement programs require a down payment between 10% and 20%. Your credit score remains a vital lever for your interest rate. While some programs go lower, aim for a score between 620 and 660 to unlock the most favorable terms. If you want a deep dive into the technical side of these programs, explore our Ultimate Guide to Bank Statement Loans. Ready to see what your deposits can actually buy? You can connect with an Arizona expert to analyze your statements today.
Owner-Occupied Hard Money: The “Last Resort” That Actually Works
Most private lenders run away from primary residences. They’re afraid of the regulatory complexity. At Applewood Funding Inc, we specialize in the rare owner-occupied hard money loan. While big banks obsess over your 1040, we focus on the strength of your asset. This is pure asset-based lending. Your home equity or your down payment carries the weight that your tax returns can’t. If you have the equity, you have a direct path to a self employed home loan no W2, regardless of what the traditional underwriters say.
Speed is your best friend in the Arizona market. While traditional closings drag on for weeks, we can often close in days. This makes hard money the perfect “bridge.” You secure the property now, move in, and stop worrying about losing your dream home to a cash buyer. It solves the immediate problem of access while giving you the breathing room to stabilize your long-term financing.
When to Choose Hard Money Over Bank Statements
Bank statement loans are excellent, but they still require a baseline of credit stability. If you have a recent bankruptcy, foreclosure, or a tax lien, hard money is your best option. The “opportunity cost” of missing a perfect home in Sedona or Scottsdale is often far higher than the temporary interest of a private loan. We look at the collateral. If you have a 25% to 40% equity position, your credit score becomes secondary. Equity is the ultimate collateral for a fast Arizona home loan when time is running out.
Refinancing Out of Hard Money
Hard money isn’t a 30-year destination; it’s a 12-to-24 month strategy. You get the house today while you age out a credit event or prepare your bank statements for a long-term Non-QM product. We help you plan your “exit strategy” before you even sign the papers. Before moving forward, it’s smart to weigh the Pros and Cons of Hard Money. We prioritize your long-term success by ensuring you have a clear path to a lower rate down the road.
How to Prepare for a No-W2 Home Loan: A 5-Step Guide
You’ve seen why traditional banks stumble and how alternative programs bridge the gap. Now, it’s time to prepare your files for a successful closing. Preparation is the difference between a smooth seven-day approval and a month of frustrating back-and-forth emails. Underwriters aren’t just checking your balance; they’re looking for a pattern of stability that justifies the loan. To secure a self employed home loan no W2, you must present a narrative of business health that an algorithm can’t reject. In 2026, lenders use AI-powered systems that flag inconsistencies instantly. Your job is to make your financial story bulletproof before the first scan.
Step 1: Document Your Business Existence
Lenders need proof that your business is a stable entity, not a temporary gig. You must show you’ve been operational for at least two years. In Arizona, this means having your filings with the Arizona Corporation Commission or a current business license in cities like Mesa or Glendale. If your specific trade doesn’t require a formal license, a letter from a CPA or a professional, active website can serve as verification. You must also prove you’re the 100% owner of the entity. If you have partners, keep your K-1 or operating agreement ready to show your specific share of the business income.
Step 2: Clean Up Your Bank Statements
Underwriters hate mystery. Every dollar that enters your account should have a clear, documented source. If you’re moving $5,000 from a savings account to your business checking, flag it early. Non-income transfers should never be confused with revenue. More importantly, you must avoid Non-Sufficient Funds (NSF) occurrences. Even a single NSF in the last 12 months can trigger a manual review or an immediate rejection. If you have a large, non-standard deposit, write a one-sentence summary explaining it now. Don’t wait for the underwriter to ask. Proactive clarity wins every time.
- Step 3: Organize Your Corporate Paperwork. Gather your Articles of Incorporation and any relevant business tax ID numbers. We need to verify the legal structure of your business even if we aren’t using your tax returns.
- Step 4: Secure a CPA Letter. This is a vital tool. A CPA letter can verify your business ownership and attest to your actual expense ratio. If your business has low overhead, this letter prevents the underwriter from applying a standard 50% “haircut” to your deposits.
- Step 5: Avoid Untraceable Cash. Large cash deposits that cannot be sourced are a red flag for modern anti-money laundering protocols. If you deal in cash, deposit it regularly and keep meticulous receipts. mattress money won’t help you buy a house in 2026.
Ready to see if your statements meet the mark? You can submit your bank statements to Applewood Funding Inc for a professional audit and get a clear answer on your buying power within 24 hours.
Why an Arizona Private Broker is Your Best Bet in 2026
Algorithms don’t buy houses. People do. When you’re hunting for a self employed home loan no W2, the last thing you need is a call center in another time zone reading from a script. Big-box banks treat Arizona like a spreadsheet. They don’t understand why a property in Peoria is valued differently than one in Flagstaff or Gilbert. They see a tax return; we see a business. At Applewood Funding (NMLS 175371), we use common-sense underwriting. This means you talk to a human being who understands cash flow, not a machine programmed to say “no” based on a single line of a tax return.
Joel McDaniel and the Applewood team give you direct access to decision-makers. There’s no corporate ladder to climb and no waiting for a committee in a skyscraper. When speed is the only currency that matters in a competitive market, local private funding is your unfair advantage. Arizona sellers want certainty. They want to know the deal won’t die in a 45-day bureaucratic underwriting cycle. We provide that certainty by moving at the speed of your business, focusing on the strength of your bank statements and the reality of your success.
Navigating the Phoenix and Scottsdale Real Estate Markets
Local appraisal knowledge is the silent deal-maker. A generic appraiser from a national firm might miss the specific nuances of a Scottsdale zip code, causing your loan-to-value ratio to tank and the deal to collapse. We work with professionals who know the Arizona dirt. For the Scottsdale entrepreneur, alternative lending isn’t just a backup plan; it’s a strategic tool to win properties that traditional buyers lose. Don’t let a faulty appraisal or a slow bank cost you your dream home. You can Get a Custom Quote from Applewood Funding and see the difference local expertise makes.
Closing the Gap Between “No” and “Homeowner”
You’ve built something from nothing. Your mortgage should reflect that success, not hide it. The path from bank statements to keys in hand is shorter than you think. You don’t need a W2. You don’t need to overpay the IRS just to satisfy a bank’s rigid rules. You need a partner who values your hustle as much as your revenue. We’ve laid out the roadmap: audit your deposits, choose the right statement program, or use owner-occupied hard money as a bridge. The house is waiting. Let’s turn those deposits into a front door. Reach out for a consultation today and let’s get you home.
Claim Your Keys with Common Sense Funding
Traditional banks are stuck in the past; your business is moving forward. You’ve discovered how bank statement loans turn monthly deposits into buying power and how owner-occupied hard money acts as a vital bridge when speed is everything. Securing a self employed home loan no W2 doesn’t have to be a bureaucratic nightmare. It just requires a partner who values your cash flow over your tax deductions. Stop letting a tax return hold you back and start working with a lender who understands your hustle.
As a specialist in Arizona non-QM loans and rare owner-occupied hard money options, Applewood Funding provides the fast, local underwriting you need in Phoenix, Scottsdale, and beyond. We don’t wait for committees; we make common-sense decisions that get you to the closing table. You’ve done the hard work of building your business. Now, it’s time to let that success buy your next home. The path to homeownership is clear, and we’re ready to help you navigate it with speed and certainty.
Apply for a Self-Employed Home Loan in Arizona
Frequently Asked Questions
Can I get a home loan with no W2 and no tax returns?
Yes, you can qualify using alternative documentation like bank statement loans or owner-occupied hard money. These programs are specifically designed for Arizona entrepreneurs who have high cash flow but significant tax write-offs. Instead of looking at your 1040 tax returns, we analyze your monthly deposits to verify your actual buying power. This allows you to secure a self employed home loan no W2 without the rigid restrictions of traditional big-box banks.
What is the minimum credit score for a bank statement loan in Arizona?
Most lenders look for a credit score between 620 and 660 to offer the best terms in 2026. While some specialized programs might consider lower scores, a higher score significantly reduces your interest rate and down payment requirements. We prioritize your overall financial health and business stability. If your score is on the edge, having strong equity or a consistent history of business deposits can often help bridge the gap during underwriting.
Is the interest rate higher for self-employed home loans?
You should expect a small premium over conventional mortgage rates. As of September 2026, bank statement loan rates typically range from 6.625% to 7.125%. This reflects the additional risk lenders take when bypassing traditional W2 documentation. If you choose a hard money bridge loan, rates are higher, often between 10% and 18%. However, the trade-off is the extreme speed and flexibility you gain in competitive markets like Scottsdale or Sedona.
How much down payment do I need for a no-W2 mortgage?
Standard bank statement programs usually require a down payment of 10% to 20%. If your situation requires an owner-occupied hard money loan, expect to put down between 25% and 40%. These equity requirements protect the lender while allowing you to skip the mountain of paperwork required by traditional institutions. Having more skin in the game often leads to faster approvals and more common-sense underwriting from local Arizona private brokers.
Can I use a bank statement loan for a primary residence in Phoenix?
Absolutely. Bank statement loans are a premier solution for primary residences in Phoenix, Gilbert, and Mesa. Many people mistakenly believe these products are only for real estate investors. Applewood Funding specializes in helping local business owners buy the homes they live in. Whether you’re a freelance consultant in Tempe or a contractor in Glendale, your business deposits can be the key to your new front door without needing a corporate paystub.
What happens if my business has one bad month of deposits?
One slow month won’t disqualify you from a loan. Underwriters typically average your deposits over a 12 or 24-month period to determine your qualifying income. This “smoothing” process accounts for the seasonal fluctuations common in many Arizona businesses. If your income is exceptionally “lumpy,” we may use a 24-month look-back to show a more consistent long-term trend. We focus on the big picture of your business success, not a single snapshot.
Do I need a CPA letter to get a self-employed home loan?
While not always mandatory, a CPA letter is a powerful tool to secure a self employed home loan no W2. This letter verifies your business ownership and attests to your actual expense ratio. Without it, lenders often apply a standard 50% “haircut” to your business deposits. If your overhead is low, a CPA’s verification can significantly increase your qualifying income, allowing you to afford a much larger home in high-value areas like Paradise Valley.
How fast can a hard money loan close on an owner-occupied home?
We can often close these loans in just a few days. Traditional banks in Arizona frequently take 45 days or more to navigate their corporate bureaucracy. Because Applewood Funding uses local decision-makers and common-sense underwriting, we bypass the red tape. In a fast-moving market like Flagstaff or Peoria, this speed allows you to compete with cash buyers and secure a property that would otherwise be lost to a slower traditional buyer.